For years, Australian businesses have been attracted to the idea of fee-free EFTPOS.
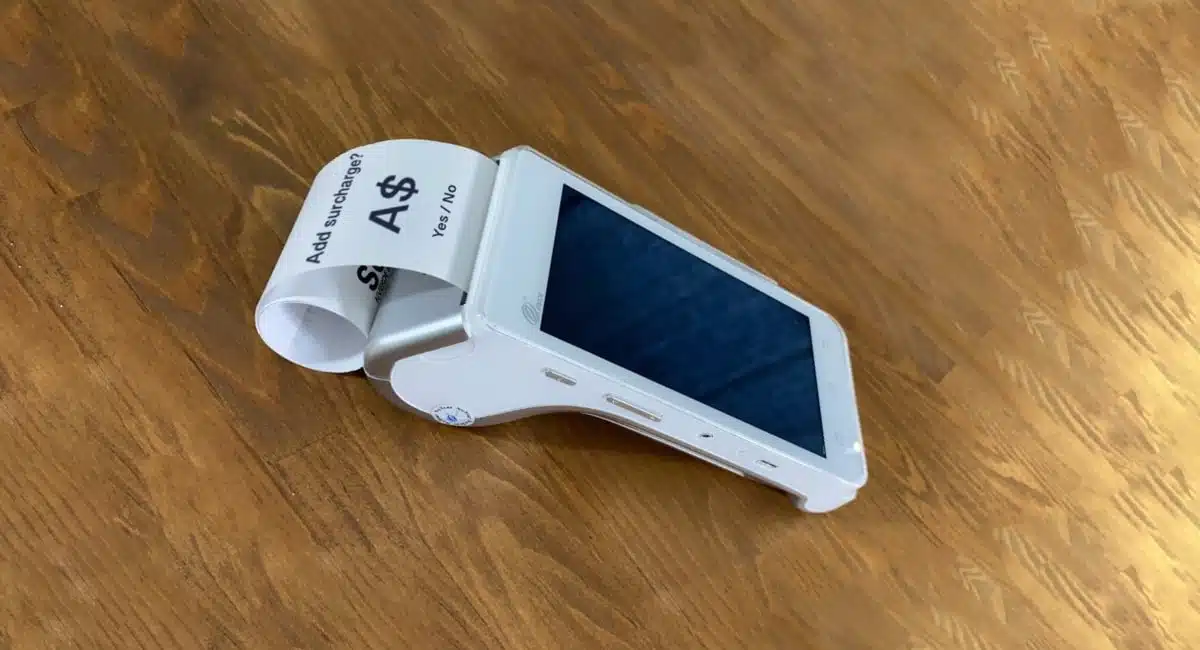
Zero-cost EFTPOS refers to card machines that let merchants pass on the card transaction fee to customers as a surcharge, to avoid paying it themselves.
From 1 October 2026, businesses can no longer add a surcharge when a customer pays with eftpos, Visa or Mastercard. American Express, UnionPay and JCB have followed suit. PayPal will join on 5 October. The “zero-cost” model is largely gone for everyday card payments.
But not every surcharge is banned. Weekend and public holiday surcharges, as well as booking and service fees, are still allowed as long as they apply no matter how the customer pays. A few payment methods outside the ban, such as Diners Club and buy now, pay later (BNPL, e.g. Afterpay), can also still be surcharged.
What surcharges are still allowed?
From 1 October 2026, only some ways of passing on fees will remain possible. Here’s what’s still allowed.
Scheduled surcharging at weekends and holidays
A way to automate surcharging is to have it automatically switched on during weekends and public holidays. This still remains relevant, especially for hospitality businesses. Not all payment providers will support it though. Square has this setting for its merchants to help them offset the higher wages they have to pay staff during those times.
Booking or service fees
These are allowed if they apply to every payment method, including cash. The catch is that a mandatory booking fee that applies only to card payments counts as a card surcharge.
Diners Club and BNPL
Amex, JCB, UnionPay and PayPal have all decided to join Visa, Mastercard and eftpos in the surcharging ban. For now, Diners Club and BNPL payments may still be subject to surcharging. Beware though, as the ban could be extended to cover these payment methods as well.
Discounts for other payment methods
Strictly speaking, this isn’t a surcharge, but it’s the sanctioned alternative: businesses can keep offering discounts for cash, bank transfers and other payment methods to steer customers away from card payments.
Taxi surcharges
The Reserve Bank of Australia has left a ban on taxi surcharging to state and territory regulators.
Passing on fees can have benefits
The obvious main benefit of surcharging was the lack of transaction fees for the merchant. If every customer paid the card processing fee applied to their transaction, the merchant only paid for the EFTPOS machine and other charges associated with it.
Some merchant service providers advertised “zero fee” EFTPOS rental contracts with surcharging, but the monthly fee was only eliminated if the business processed enough card transactions. Notable offers were Shift4’s Zero Cost EFTPOS and PayNuts’ Pay Nothing plans.
Zero-cost plans also made card acceptance more accessible to small businesses unable to afford upfront terminal costs or fixed monthly fees.
Your customers may not like it
In spite of the benefits for the merchant, customers don’t like getting surcharged. This is likely to be even more true after 1 October 2026. With the card surcharge ban widely reported, customers will expect extra fees at the counter to be a thing of the past.
Even a perfectly legal weekend surcharge or service fee may be met with suspicion. Make sure any remaining surcharge is clearly displayed before they order or reach the checkout, so it doesn’t come as a surprise.
Consumers have become more used to card payments and don’t want to get penalised with a surcharge for just trying to use a card. Then you have some people who don’t carry cash, so paying by card is the only option for them.
The fact is cash costs money to accept too, when you consider the time it takes to cash up, banking fees and the security risk of storing money on premises.
If a customer doesn’t want to – or can’t – pay a surcharge, you run the risk of losing that sale entirely. The person might say they’ll go out to get cash, then never return. Or they’ll simply get annoyed and go elsewhere to buy the items.
Your obligations from 1 October 2026
If you decide to continue to surcharge, there are certain rules businesses have to follow in Australia:
- Weekend, holiday and service fees must apply to everyone. They are only allowed if they don’t depend on the customer paying by card, and prices still need to be displayed clearly.
- Discounts are allowed, with a condition. A discount for another payment method must not make the undiscounted price unclear or less prominent.
- Diners and BNPL. If a business surcharges these, it should check the provider’s rules first.
The Reserve Bank of Australia will monitor the situation, and further changes may well follow.