Coming from Europe, SumUp entered Australia in 2023 with a low-cost card reader to compete with Square. Its offering has expanded rapidly since, with several EFTPOS terminals and a growing range of POS and online payment tools.
It is still early days for SumUp in Australia, though. Some services are being rolled out, and its local operation is not yet as established as Square’s. But is SumUp now a serious alternative to Square for small businesses?
We at Mobile Transaction have tested both payment companies for years. Typically, our tests find Square superior for its excellent-value payment tools to complement its EFTPOS machines, while SumUp’s EFTPOS and payment products are simpler and cheaper, but also more limited.
 |
 |
|
|---|---|---|
| Products | Card processing, EFTPOS machines, payment tools | Card processing, EFTPOS machines, POS (advanced), payment tools, marketing suite, staff/shift management, loans |
| Contract | No lock-in, pay-as-you-go | No lock-in, pay-as-you-go |
| Card rate | Chip, tap: 1.4% Online: 2.1% |
Chip, tap: 1.6% Online: 2.2% |
| Payouts | 1-3 business days | Next day, including weekends. Immediate with Instant Transfers |
| Accepted cards |      |
|
| Card machines, purchase cost | $49–$249 incl. GST | $65–$349 incl. GST |
| POS systems | SumUp App (free) | Square Point of Sale (free) Square for Restaurants Square for Retail Square Appointments |
| Remote payments | Payment links, online store (simple), invoicing | Payment links, online store, virtual terminal, invoicing |
| Contactless wallets |    |
 |
EFTPOS machine offerings are close, with Square in the lead
Square and SumUp both offer a range of payment hardware. The SumUp offering is stronger for mobile merchants or those looking for very low start-up costs. It offers three small low-cost mobile EFTPOS terminals without a receipt printer: SumUp Air that connects with a payment app and standalone terminals Go and Solo.
Square sells an app-based card reader, Square Reader, which connects to a phone. The strength of Square though is its point of sale software with product library and useful tools for all types of businesses whether hospitality, retail or service. The two standalone “smart” EFTPOS machines, Square Terminal and Square Handheld, shine with this pre-installed software.
Square also has two POS terminals for over the counter sales, Square Stand and Square Register. SumUp has recently been catching up, though its Smart Terminal and POS Register are still not as versatile as that of Square.
Both Square and SumUp also offer self-checkout kiosks. Overall, the ranges of both are pretty impressive. The Square hardware does feel a bit more up market, while SumUp is slightly more affordable.
Let’s compare the card readers, which are popular for its extremely low cost, as they use the processing power of a phone or tablet to accept payments. Though both have a long battery life and connect with a free app for iPhone, iPad and Android devices over Bluetooth, the card readers look very different and the apps are not equally useful for everyone.
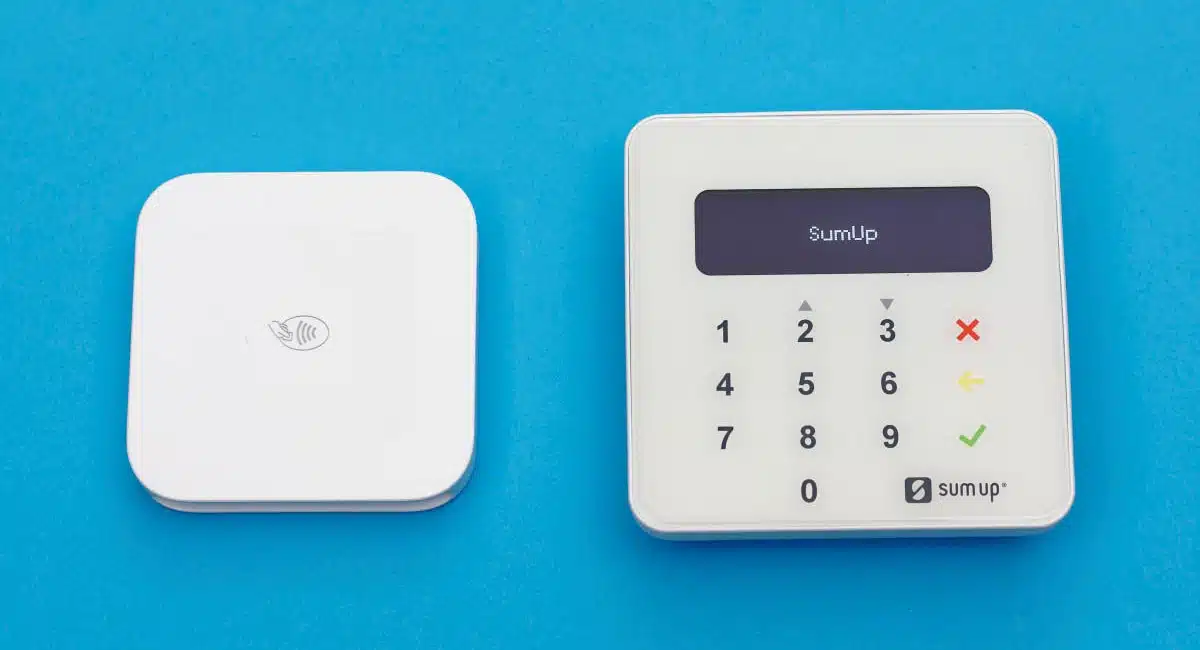
Square Reader is literally a small, square-shaped, plastic box with a chip card slot and contactless surface for tap-and-go. If a PIN code is required, a virtual PIN pad shows on the connected smartphone or tablet. SumUp Air is bigger, with a glass-surface display and PIN pad, so if a PIN code is requested, customers can enter it on the card reader.
Photo: MobileTransaction
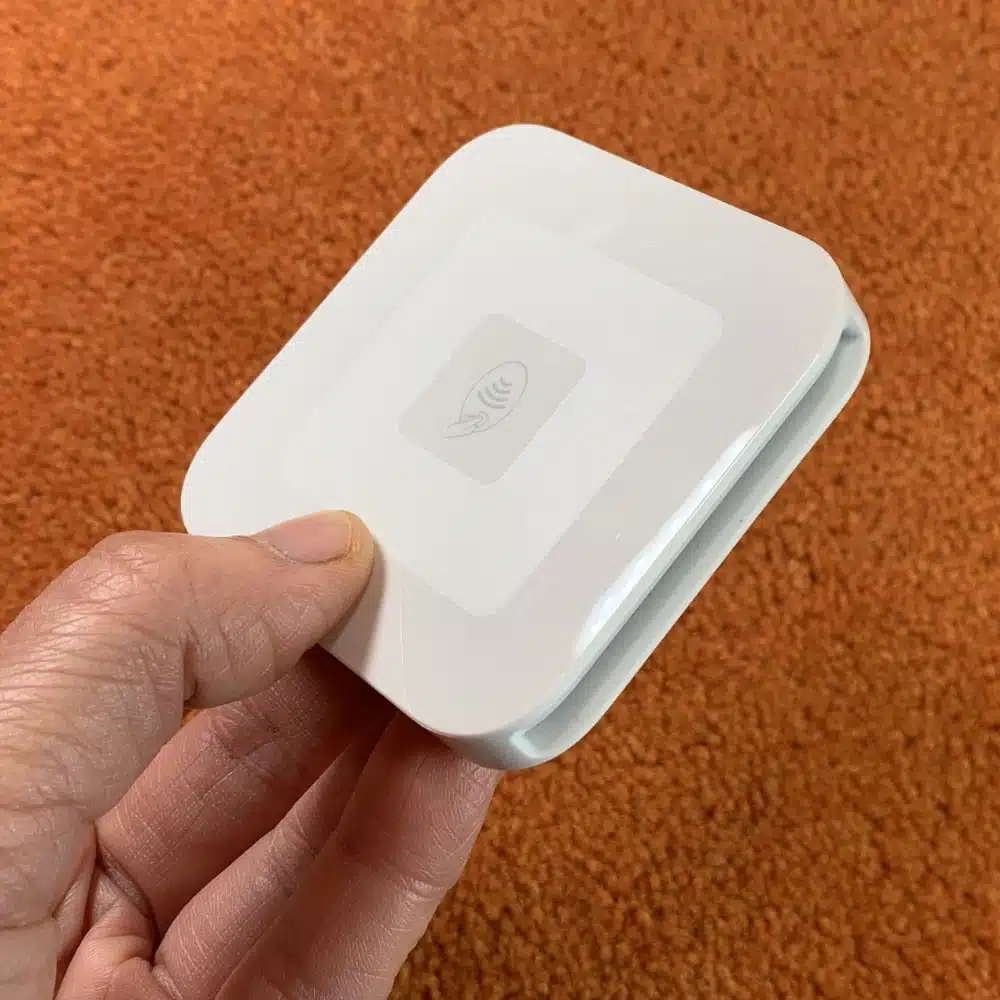
Square Reader has no PIN pad, but is small.
Photo: MobileTransaction
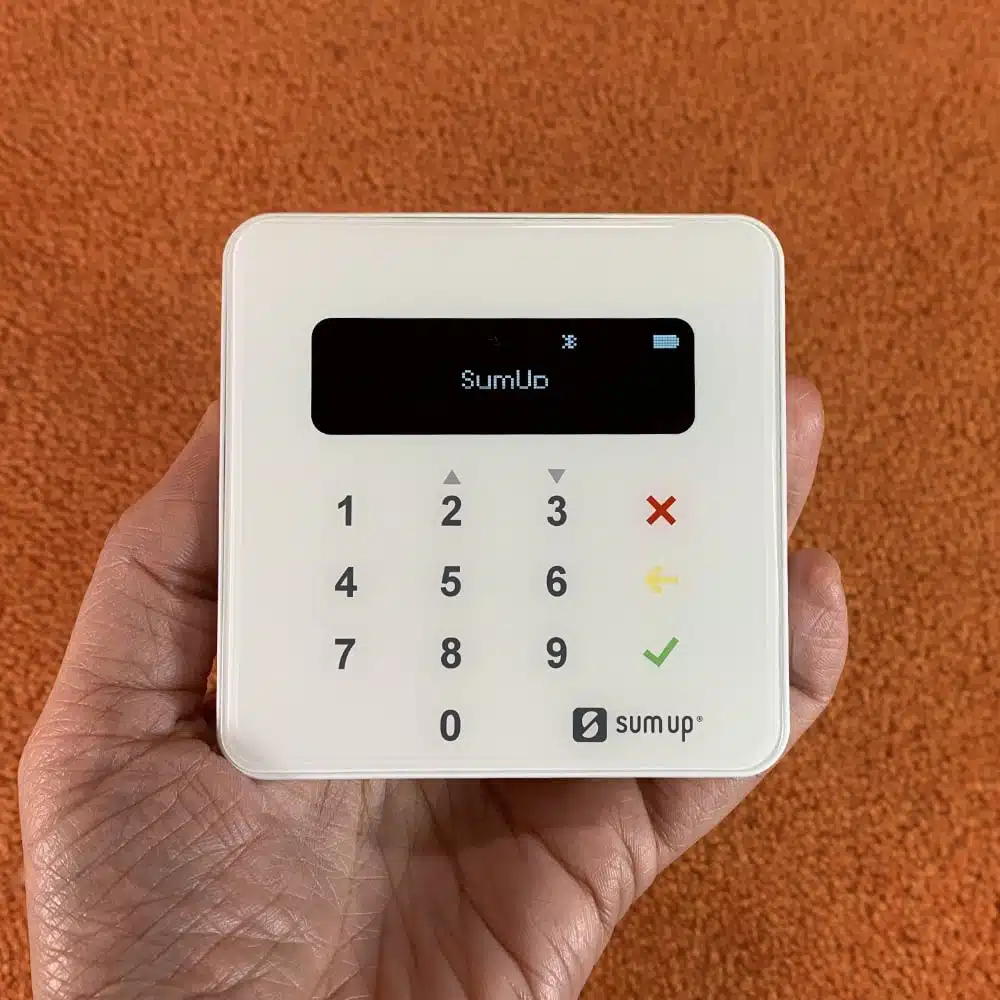
SumUp Air’s glass PIN pad is easy to clean.
We like Square Reader for its tiny size and light weight, which can equally be problematic since it’s so inconspicuous it can get lost. If at a checkout, we recommend getting the card reader stand that Square sells to keep it stationary and safe.
SumUp Air looks very unique in Australia and not everyone will like its PIN pad which is hard, smooth glass, not the sort of push-buttons that people hard of seeing would prefer. It is stylish, though, and the glass is quick and easy to wipe clean.
“We love Square Reader for its tiny size and excellent app, whereas SumUp Air avoids the awkwardness of PIN entry on a separate mobile device. It’s really down to personal preference which is better.”
– Emily Sorensen, Senior Editor, Mobile Transaction
These card readers are ideal for mobile merchants, since they use a smartphone’s or tablet’s SIM connectivity (or WiFi) to process transactions. SumUp also offers two standalone devices with their own SIM-card suitable for mobile use: Go and Solo. The latter is our favourite, with a design unique to SumUp. It can be connected to a mobile printer for a small addition to the purchase cost.
Photo: Mobile Transaction
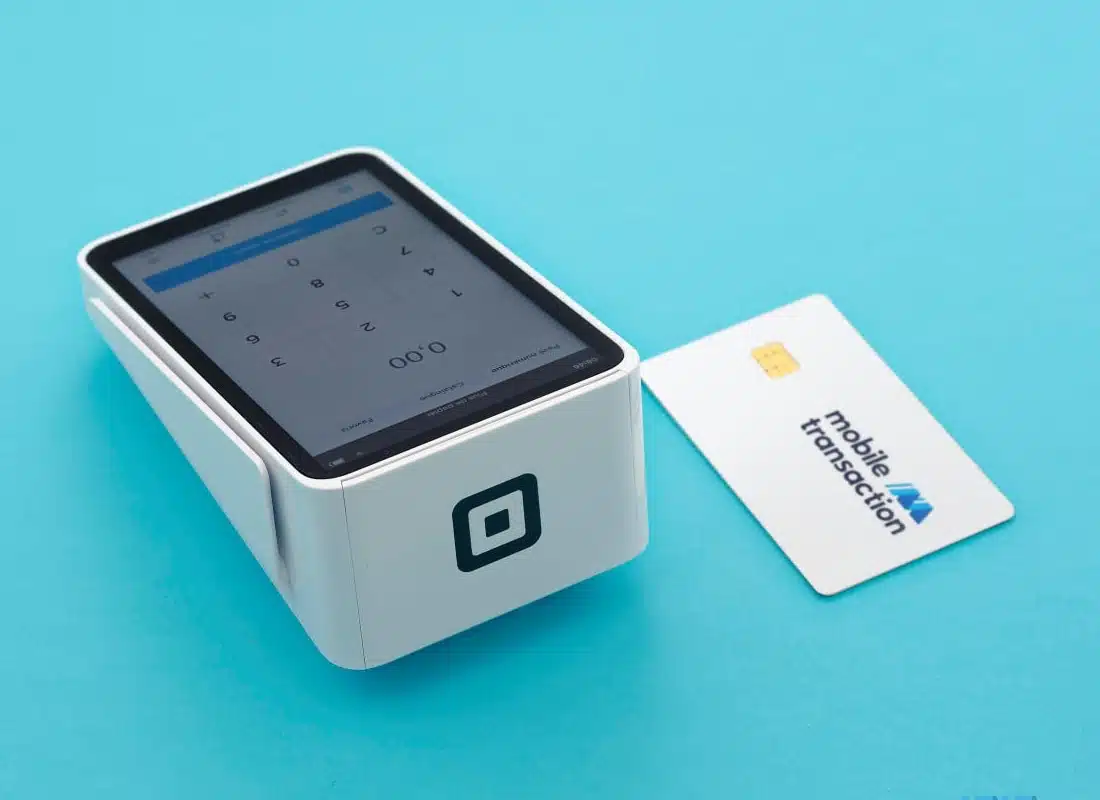
Square Terminal depends on WiFi, not mobile connectivity.
What if you need something more substantial for fixed premises?
That’s where Square is ahead with its standalone EFTPOS machine, Square Terminal. For hospitality businesses, Square also offers Square Handheld, a smart terminal with built-in POS for tableside orders and payments.
The newly launched SumUp Smart Terminal is not far behind, and the design is slightly more elegant than what we are used to seeing from SumUp.
Photo: Mobile Transaction
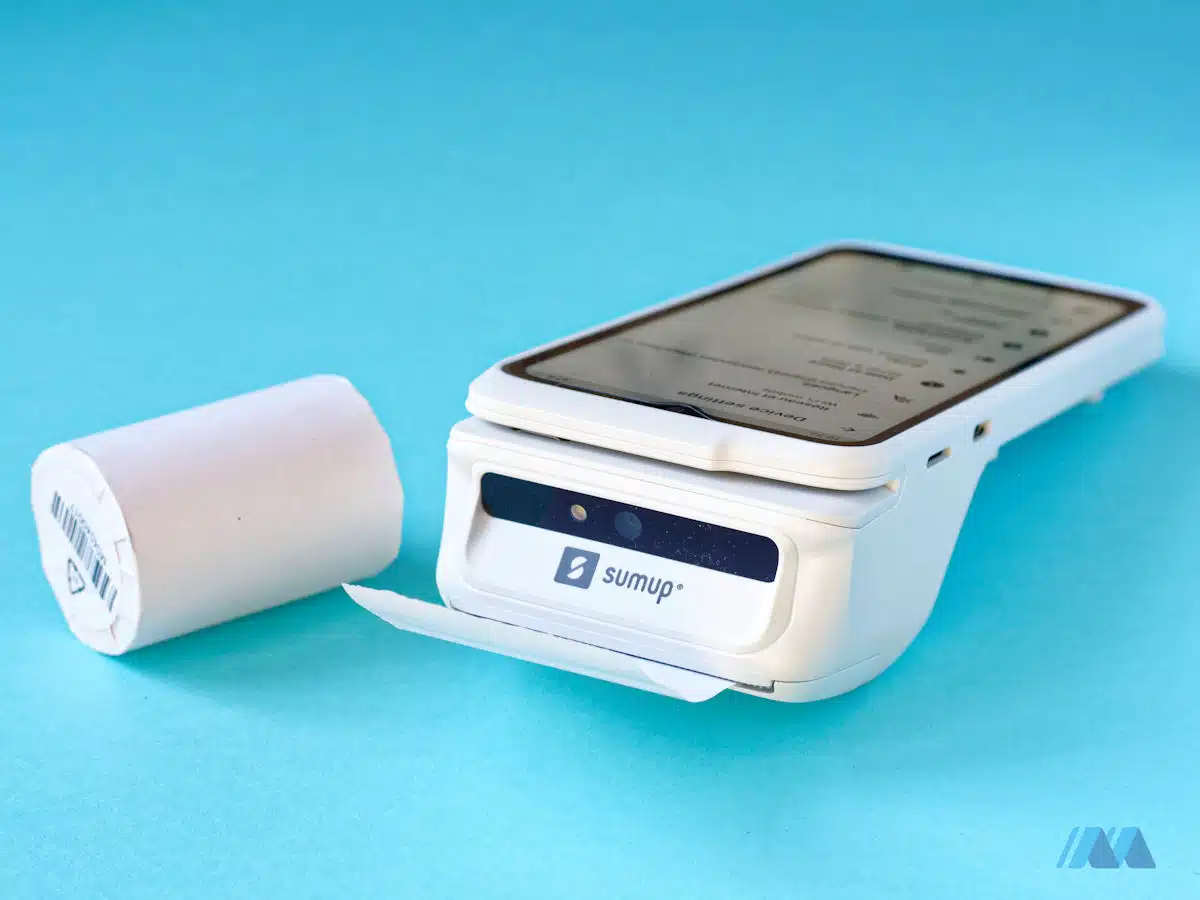
The Smart Terminal from SumUp sits well in the hand, and comes with a pre-installed product library, analytics, and other tools.
Square Terminal only works with WiFi or Ethernet (if using a connector cable), not 3G, 4G or other mobile connection since it has no SIM card. Still, it is wireless, portable and prints receipts, so ideal for table service and point-of-sale setups alike.
Its large touchscreen comes with Square Point of Sale software preinstalled so no other register screen is needed (though it does connect with Square POS on an external screen). The default software is the same as the free app used with Square Reader.
Tap-on-phone with both Square and SumUp
Those without a card reader can use Tap to Pay on iPhone or Android, where customers tap their card or mobile wallet directly on your smartphone to process a transaction – no EFTPOS terminal needed.
Fees: simple pricing without contract
The fees of SumUp and Square are very similar. Both have pay-as-you-go pricing where you buy an EFTPOS terminal upfront and only pay transaction fees when payments are processed. The main difference is in the cost of terminals and associated rate for chip and tap card payments:
A slightly higher fixed transaction rate applies through Square at 1.6% than SumUp at 1.4%, so the latter is cheaper both to purchase and use for card payments.
The above transaction rates are fixed regardless of the card brand (eftpos, Visa etc.), type (debit, credit, commercial, consumer, etc.) as long as the card is issued in Australia. Both providers accept the same range of cards, which includes American Express and JCB. Square adds another 1.5% on international cards.
| Costs | |
|
|---|---|---|
| Card reader with app | Air: $49 incl. GST | Reader: $65 incl. GST |
| Standalone terminal | Solo: incl. GST Smart Terminal: $249 incl. GST |
Terminal: $329 incl. GST Handheld: $349 incl. GST |
| Website | ||
| Chip, tap payments | 1.4% | 1.6% |
| Afterpay transactions | Not available | 6% + 30¢ + GST |
| Pay-by-link transactions | 2.1% | 2.2% |
| Invoice | 2.1% | 2.2% |
| Keyed transactions (virtual terminal) | Not available | 2.2% |
| Instant transfers | Not available | 1.95% added to transactions |
| Chargebacks | Fee applies | Free |
| Refunds | Free before payout, transaction fee retained after | Original transaction fee is retained |
Square charges 2.2% for online and keyed payments, whereas SumUp charges slightly less (2.1%) for payment links. This makes sense, since Square’s online payment features are much more elaborate so you’re paying more for the quality of it.
The Buy Now Pay Later option Afterpay is accepted by Square at the point of sale and online, for 6% + 30¢ (excl. GST) per transaction. This looks expensive, but can still boost sales. SumUp doesn’t offer any Buy Now Pay Later options as of yet.
None of them have contract lock-in or monthly fees, so it’s risk-free to sign up and test the services. You don’t even need to cancel the account, as it will just stay dormant until next time you need it.
Square has no fees for chargebacks, whereas SumUp does when a customer disputes a transaction through their bank.
If you refund a SumUp transaction within 2-3 days (before the payout is settled), there’s no charge – otherwise, it costs the original transaction fee. Square always retains the transaction fee for refunds processed.
Square has tons more than just EFTPOS solutions, some with a subscription like the online store ($0-$99/month on annual plan), invoicing ($0-$30/month) and email marketing ($20-$50/month). SumUp doesn’t offer additional features with fees.
Square has the faster settlement
Neither platform charges for standard payouts to your bank account, which take:
- 1-3 business days through SumUp
- Next day through Square, including weekends
Not only does Square have the edge with its slightly faster release of funds, it also offers Instant Transfers to your bank account (optional setting for eligible users). This incurs a 1.95% transfer fee on top of the transaction fee.
When Instant Transfers is switched on, you receive card payments within minutes. Square is one of very few Australian payment companies to offer this, so that’s an edge over SumUp.
POS: limited with SumUp, room for growth with Square
Apart from EFTPOS terminals, the companies offer a few point of sale (POS) registers.
The simplest is SumUp Point of Sale Lite, a branded white stand with a tablet built in that connects with Air for card payments. It can only use the free SumUp App as its POS software, which has many core features, but not sufficient for a restaurant or complex retailer.
Square Stand looks similar and even has a contactless function and chip card slot, but it requires an iPad to be placed inside. This enables you to use it with different POS systems for any industry.
Photo: SumUp
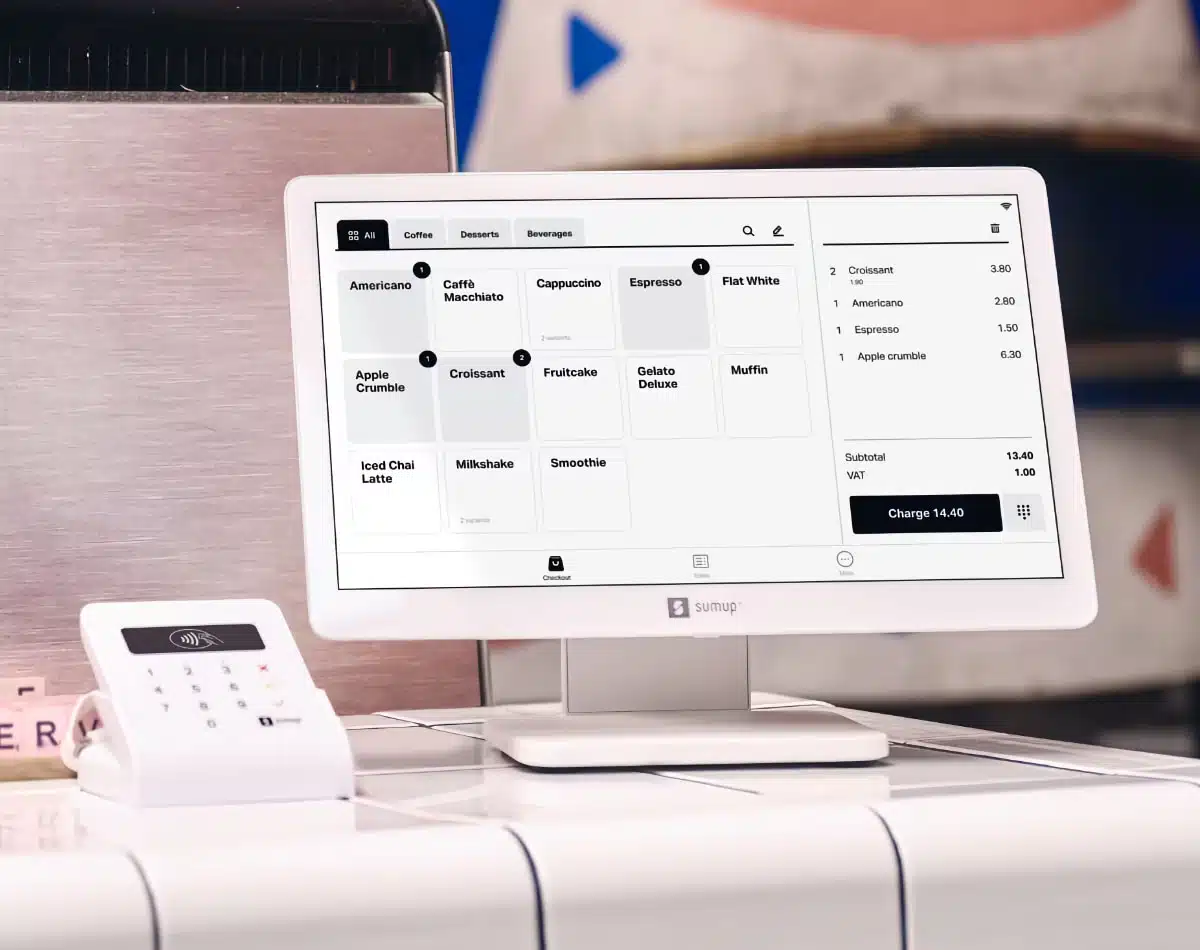
SumUp Point of Sale Lite register looks modern, with simple but functional POS software.
For a more premium product, there is also the tablet register Square Register (no iPad needed) with a fancy-looking touchscreen card reader attached. This is, in our opinion, the easiest all-in-one tablet register in Australia so far, but it does cost more and is hardwired to work with Square’s software.
Photo: MobileTransaction
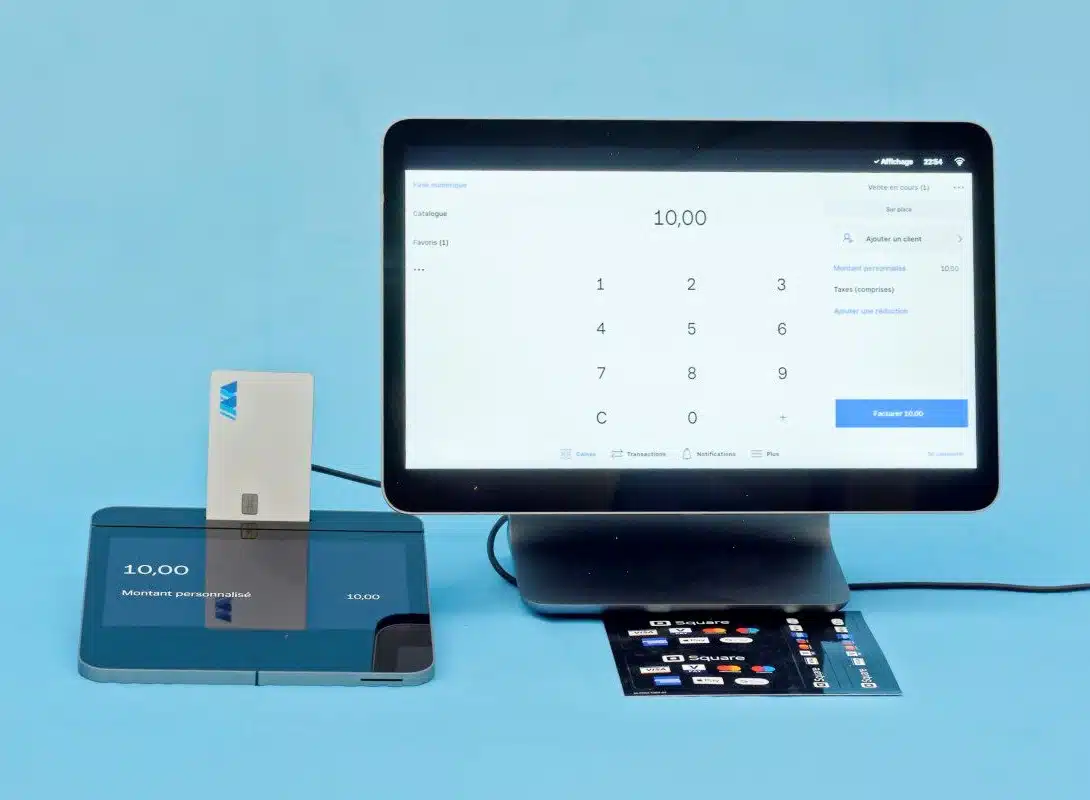
Square Register has its own EFTPOS machine built in, and check-out with the touchscreen was intuitive in our test.
So how does the software compare?
For a start, both have sales reports in an online ‘Dashboard’, but Square’s are very customisable while SumUp’s are more basic.
SumUp only offers one POS system. This is either used via the SumUp App (free), or purchased pre-installed in the register hardware POS Lite. It has enough features to run a simple checkout in a shop, café or other small operation.
Square’s comparable Point of Sale app (free) also caters to general needs, but with noticeably more features.
Both have an inventory library with product variants, discounting and GST rates. There are options for tipping, cash acceptance and refunds, and transactions and payout statuses can be accessed in the apps. Staff members can have their own logins with restricted access to certain features.
On top of that, Square has more features like stock counts, employee and customer management, split tenders and marking transactions for eat-in or takeaway. You can view sales reports in the Square POS app and sell or accept gift cards.
Square also has upgrade options: Square for Restaurants ($0-$129/month), Retail ($0-$109/month) and Appointments ($0-$90/month). These are different POS apps designed for food-and-drink, retail shops and professionals using a booking system.
SumUp has been catching up in 2026 though, introducing SumUp Booking for service businesses and a kitchen display system for busy food venues.
The Square platform can even be extended with dozens of third-party apps for advanced functions like inventory management, online ordering, ecommerce, accounting and marketing. SumUp doesn’t yet connect with other software in Australia, so is much more limited.
Many versus few online payment methods
The two payment companies have become more similar in what type of online payments they offer.
Both offer payment links, which can be sent via email, SMS, social media or copied and pasted into any message online. The recipient gets a link for an online checkout page where their card details are entered to complete the requested transaction. They both also offer:
- Email invoicing with payment tracking
- Ecommerce store builder with an online checkout, with Square Online being the most advanced
- QR code payments
On top, Square includes these features without any other cost than the transaction fee:
- Virtual terminal for keyed, over-the-phone transactions
- Recurring payments for subscriptions
Our own experience of Square’s features is consistently positive, and they have an edge from a user perspective over SumUp. They are easy to use from an internet browser or app, yet flexible with its optional functions and rarely with bugs because the software is frequently updated.
Square more extensive, SumUp a bit cheaper
Out of the two, Square is much more established in Australia, so it’s unsurprising that its payment products are broader.
SumUp, on the other hand, boasts the lowest transaction rate for an app-based card reader, and the cheapest card reader all-round. Even online transactions are lower with SumUp: 2.1% versus Square’s 2.2%.
To some degree you really get what you pay for. The slightly higher cost of Square’s products gives you more complimentary features and upgrade options than SumUp currently offers. What’s more, Square’s instant transfers are very attractive for cash-strapped merchants reliant on quick funds to get by.
For sure, SumUp has already introduced an impressive payment suite in Australia. Some merchants might want to wait until its products and services are even more “tried and tested” in Australia, while others might be willing to take a chance.