Smartphones can completely replace a dedicated card reader and process payments on their own.
How so? Through the contactless technology Tap to Pay on iPhone/Android (not to be confused with ‘tap and go’, which just means contactless payments in general).
We’ve found that this payment method is most popular as a supplement to an EFTPOS machine. For some tradies though, it’s a complete substitute.
In this article, we explore how to use your phone as an EFTPOS machine and compare the options in Australia.
Image: Mobile Transaction
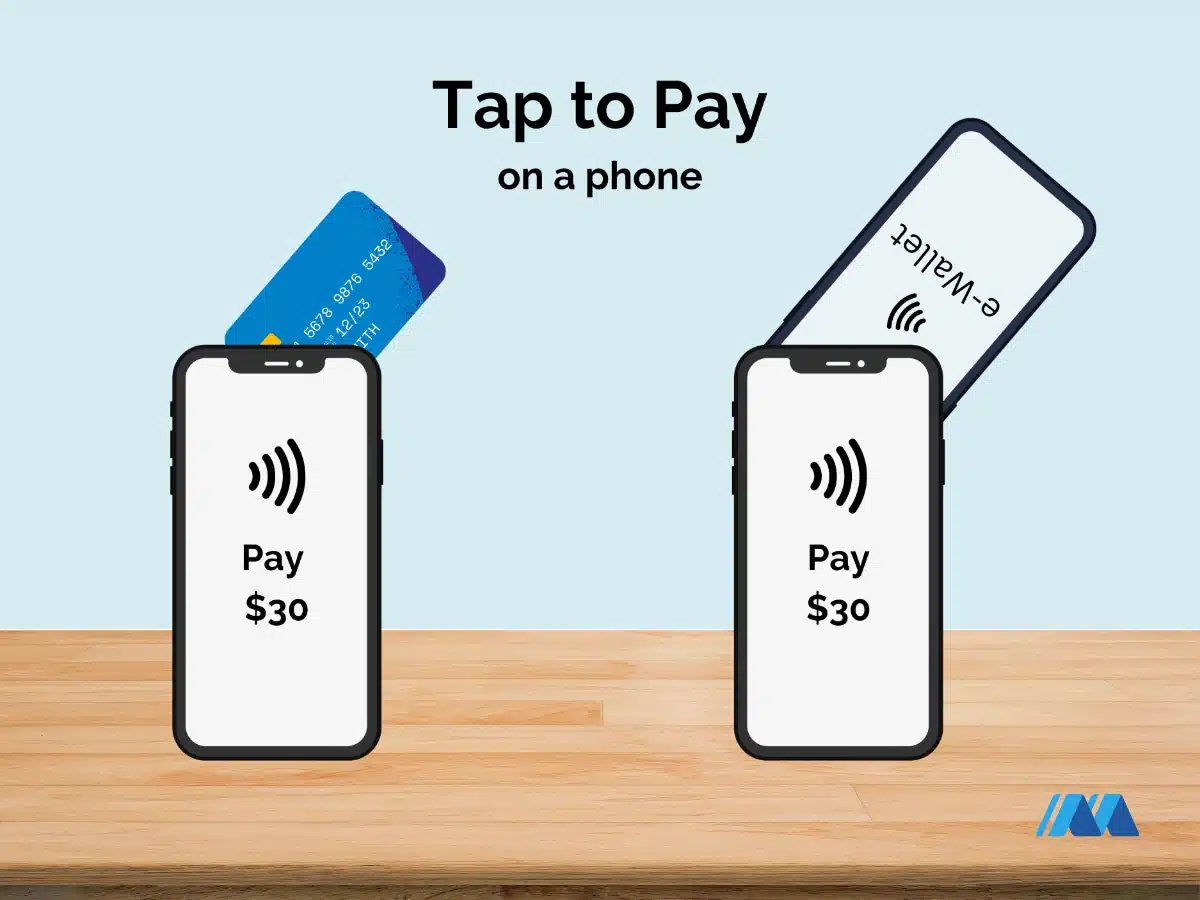
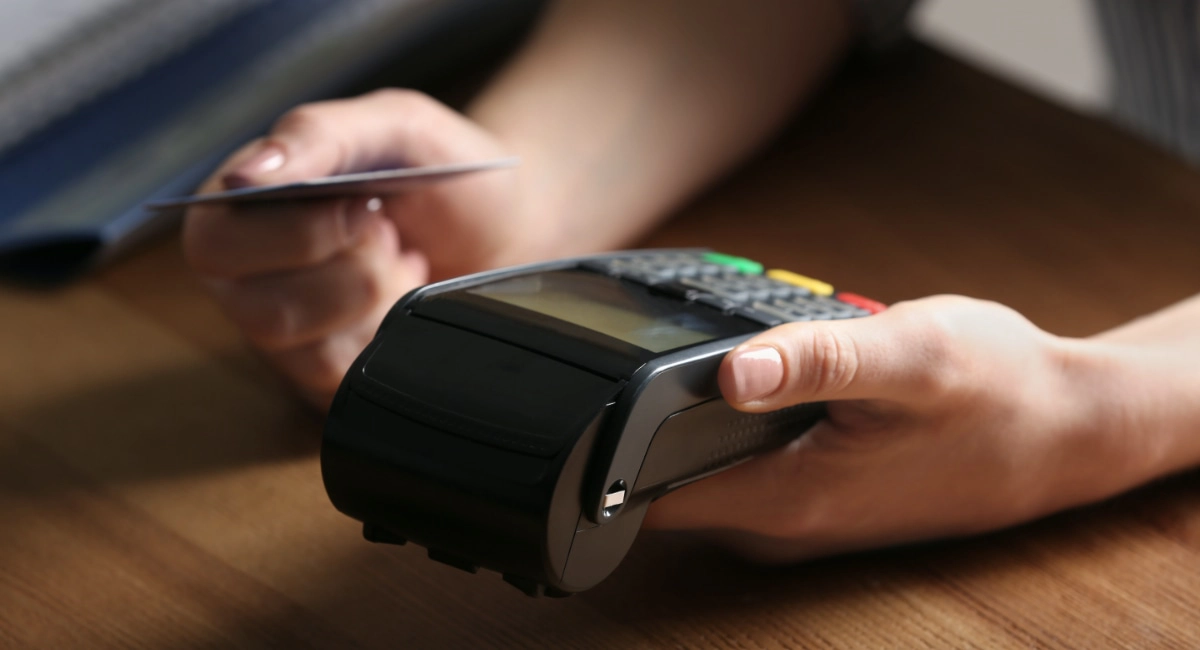
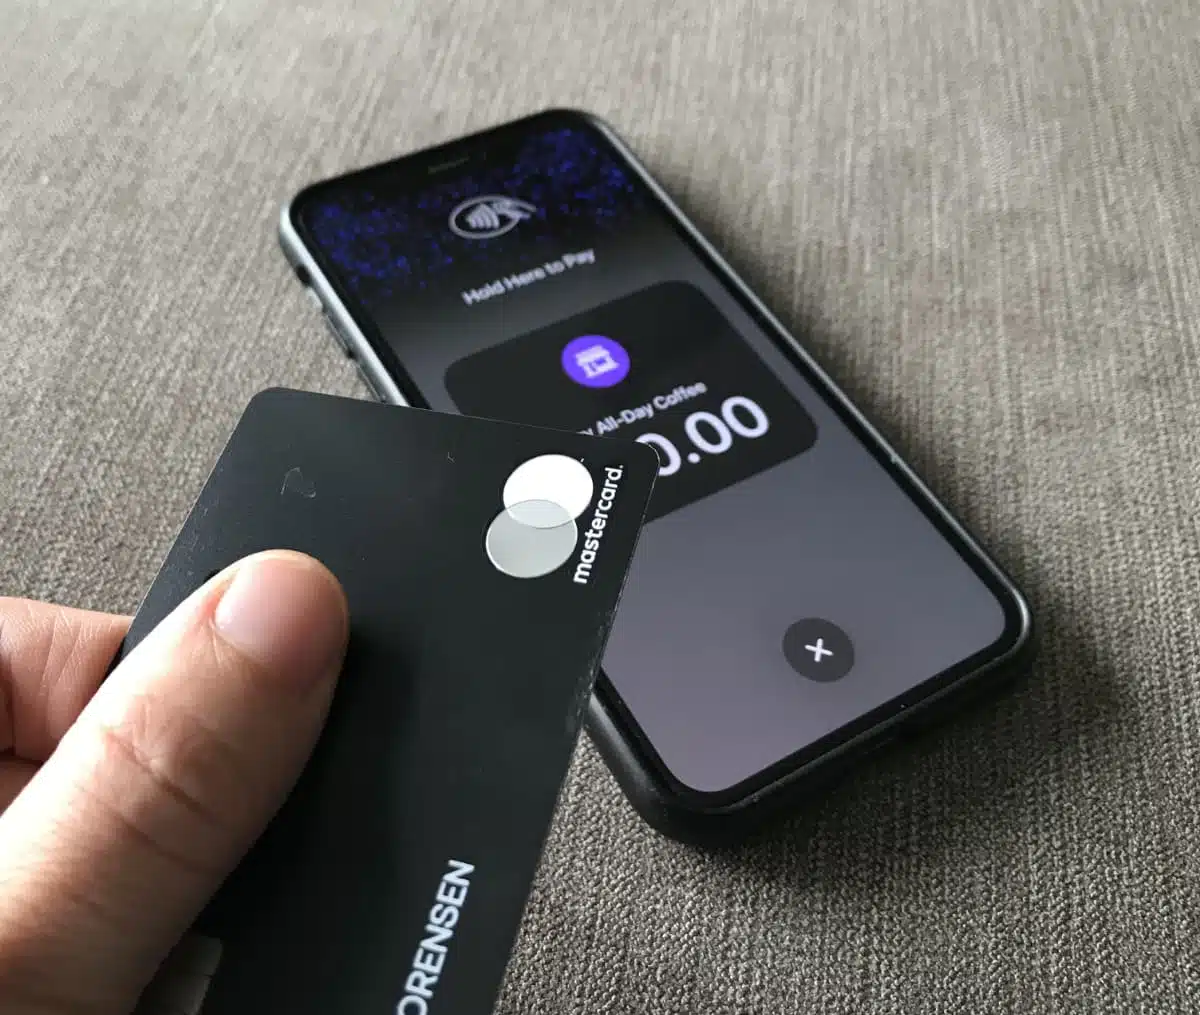
Tap to Pay works with both contactless cards and mobile wallets.
Tap to Pay solutions in Australia
In 2026, Australian merchants have plenty of ‘EFTPOS on phone’ choices.
In an effort to stay competitive, many well-known EFTPOS companies have introduced their own Tap to Pay options. These are usually separate apps or features added to their existing apps.
Complete overview of mobile EFTPOS apps with Tap to Pay in Australia:
| Solution | Android | iPhone | Costs | Key info |
|---|---|---|---|---|
| Square | Yes (offer) |
Yes (offer) |
1.6% /transaction, no monthly fee or contract | Quick and easy to start, fast payouts |
| Zeller | Yes (offer) |
Yes (offer) |
1.4% /transaction, no monthly fee or contract | Easy sign-up online, support every day |
| Westpac | Yes | Yes | 1.4% /transaction, no monthly fee | Good business account, but high-maintenance service and sign-up |
| ANZ Worldline | Yes | Yes | 1.3% /transaction + other fees, no contract | Sign-up not quick or wholly transparent |
| Revolut Business | X | Yes (offer) |
1.4% or 2.7% (international cards) + $0.20 /transaction, from A$15/mo | Multi-currency account, 24-hour payouts |
| Tyro | Yes | Yes | 1.4% /transaction, no monthly fee | Okay product, but mixed service |
| NAB | Yes | X | 1.4% /transaction, no monthly fee or contract | Same-day funds in NAB bank account |
| Shopify | Yes | Yes | 1.75%-5% /transaction, plans from A$42/mo | Feature in Shopify POS app, but only worth it with online shop |
| SumUp | X | Yes | 2.1% /transaction, no monthly fee or contract | Simple product with little presence in Australia |
| Pebl | Yes | Yes | 1.8% /transaction, no monthly fee or contract | Fairly new company with few users |
| Airpay | Yes | X | 1.29%+ /transaction, A$29 one-off licence fee, 1-year contract | Outdated service with unnecessary lock-in |
| Stripe | SDK* only | SDK* only | 1.7% or 3.5% (international cards) + $0.25 /transaction, no monthly fee or contract |
Requires coding a custom solution |
| Adyen | SDK* only | SDK* only | Custom fees | For companies with high sales volume |
* Software development kit (SDK) for adding Tap to Pay to your own payment app.
Out-of-the-box solutions
In Australia, the following providers offer Tap to Pay out-of-the-box on both iPhone and Android devices:
- Square
- Zeller
- Westpac
- ANZ Worldline
- Tyro
- Shopify POS
- Pebl
At Square, it’s available in an iPhone or Android app that also connects with Square Reader, sends payment links and accepts QR code payments. Merchants signed up with Zeller can enable Tap to Pay in its main app.
Although Square offers the most adaptable, user-friendly features we have tested, its transaction rate of 1.6% for Visa, Mastercard, eftpos and Amex cards is not the lowest. For sellers using Tap to Pay occasionally, the fee is still highly competitive for the quality and reliability. Merchants expecting higher volume may want to shop around.
Zeller, Westpac, NAB and Tyro charge 1.4%, also without monthly fees or a contract (in most cases). ANZ Worldline charges even less per transaction – 1.3% – but comes with hidden fees.
SumUp charges the highest rate (2.1%) with its EFTPOS app for iPhone, and doesn’t yet offer Tap to Pay on Android. Newcomer Pebl has a slightly lower rate, 1.8%, and some useful app features like invoice reconciliation.
Revolut’s Tap to Pay on iPhone has a fixed fee (A$0.20) on top of a rate (1.4% for domestic cards, 2.7% for others), so can end up expensive for low amounts, and the account has a monthly fee. However, global businesses will like their multi-currency features.
Shopify requires a monthly fee for ecommerce with a POS app included, with high Tap to Pay rates (1.95% or 5% on their cheapest plans). It therefore only makes sense to use Shopify if you’re already running an online shop through it.
Only Android users can opt for NAB and Airpay, though we don’t recommend the latter because Airpay’s fees are higher (rates go higher than 1.29%) and require a year’s commitment.
Photo: Mobile Transaction
The complex solutions
Stripe and Adyen are both intended for developers and large businesses wanting to add Tap to Pay functionality into their own software. We therefore don’t recommend them for individual entrepreneurs or small businesses that just need to accept contactless payments.
On the other hand, Xero has Stripe integrated in its accounting software, so accounting users could sign up with Stripe to accept contactless taps.
Global account provider Airwallex will also launch Tap to Pay functionality that developers can add to their company’s own app. Like Stripe and Adyen, Airwallex is only suited for businesses with the resources to handle custom set-up.
Advantages
Disadvantages
A couple of the disadvantages relate to customers having to touch and hold the phone.
Sometimes, a Tap to Pay app might ask for a PIN code, mainly when the transaction amount exceeds the contactless limit ($100 or $200 for physical cards). The merchant is then forced to give the customer the smartphone so they can enter the code on the touchscreen.
This is not the most hygienic solution, and customers may also be reluctant to enter their card PIN on a stranger’s phone if they’re concerned about security.
Some merchants consider buying a dedicated phone for this purpose, but then why not buy a card reader that’s cheaper and less likely to be stolen?
Photo: Mobile Transaction
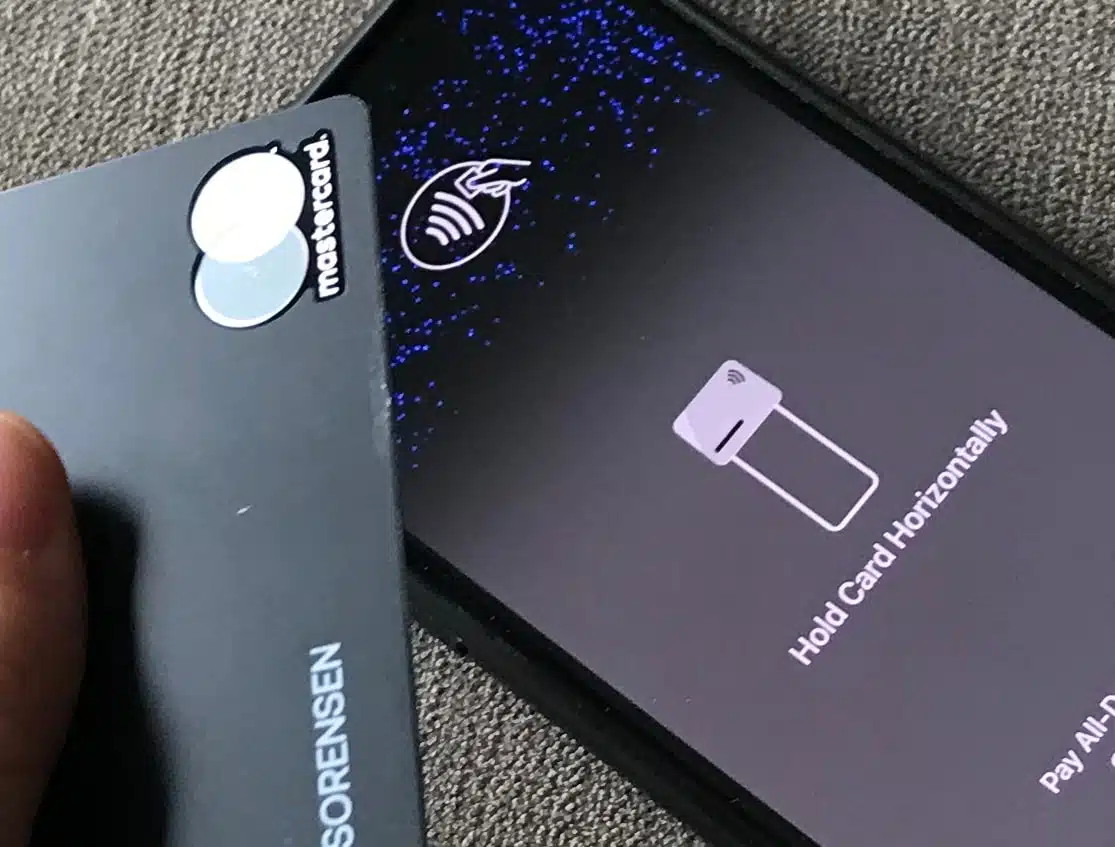
Your EFTPOS app will show simple prompts during a tap transaction.
In addition, tap-to-phone only processes contactless payments, not chip cards that have to be inserted. If a chip card doesn’t have a contactless function, your smartphone will be useless.
Also, even the most modern smartphones need to be charged more frequently than dedicated EFTPOS readers. On the go, we recommend investing in a power bank to avoid having your phone run out of battery, if that’s your only way to accept cards.
So when can it be a good solution?
Tap to Pay could be considered a secondary card reader for emergency situations (e.g. during technical issues with an EFTPOS terminal or WiFi) or payments from customers who don’t have cash (if you try to be a cash-only business).
Card reading on a smartphone is also useful for home deliveries and shops, bars and restaurants with large serving areas. Portability is, in fact, the main advantage of tap-and-go on phones.
I’ve noticed people have got more used to seeing phones used as an EFTPOS reader, so merchants no longer need to fear it’s too controversial for customers.
Is a card reader better than Tap to Pay?
Mobile card readers are inexpensive EFTPOS terminals paired with a phone via Bluetooth that’s connected to the internet. They are extremely portable and lightweight devices designed for the sole purpose of processing card payments.
Unlike a purpose-built card reader, a phone with Tap to Pay has many apps that not only drain its battery, but also make it more vulnerable to technical issues.
Image: Mobile Transaction
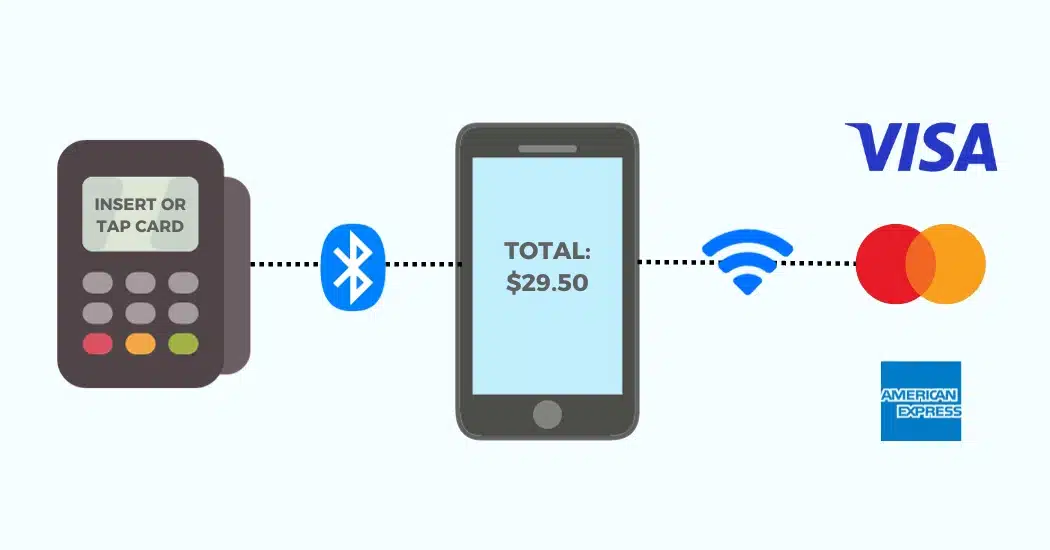
Inexpensive card readers connect via Bluetooth with a smartphone to accept card payments.
Here are some of the most competitive card readers in Australia:
The most popular phone-dependent card reader, Square Reader, can be purchased for $65 incl. GST. It has no contractual lock-in or monthly fee, just a rate of 1.6% per transaction.
Square is popular for its instant transfer option for an added fee, free next-day payouts (weekends too) and many payment tools without a contract.
Smart Mini by CommBank is sometimes offered free, but normally costs $59 with a transaction fee of 1.1% for Mastercard, Visa, American Express, UnionPay, JCB and eftpos cards. It may have hidden fees, but could be your most convenient (and cheapest) option if banking with CommBank.
European payment company SumUp has launched its inexpensive Air card reader in the Australian market, but is yet to gain a significant market share.
Why mobile card payments are popular
Although no regulations in Australia require businesses to have a card reader or accept card payments, many consumers avoid using cash. Still, some merchants are reluctant to accept cards.
That’s because banks and traditional merchant service providers often have inflexible terms for small, new businesses with limited sales. This could involve monthly charges and a raft of of EFTPOS fees affecting the bottom line.
Card surcharging has traditionally helped businesses recover payment processing costs. However, from 1 October 2026, merchants will no longer be able to add surcharges to payments. This makes choosing a provider with competitive transaction fees even more important.
This is where smartphones have come to the rescue of small merchants. Mobile card readers and Tap to Pay are typically affordable and mostly without commitment or complicated fees.