Two of Australia’s more interesting EFTPOS solutions, Square and Shift4 (previously Smartpay), were actually founded in the US.
They both cater to small businesses in Australia, but not in the same way. Smartpay has historically focused on EFTPOS machines with surcharging, which Shift4 continued following its acquisition of the company. Square offers a range of EFTPOS terminals, but the big draw is a broader range of business tools on the same platform, saving sellers time.
We look at their EFTPOS machines, pricing and critical aspects of their offering to understand which is better, especially considering the new surcharging ban.
 |
 |
|
|---|---|---|
| Upfront cost | None (rental) | $65 – $349 incl. GST (purchase) |
| Transaction fee | Variable | 1.6% |
| Monthly cost | Min. $100 + GST monthly | None |
| Payment methods | Terminals, over the phone | Terminals, payment links, over the phone, invoices, on website |
| Hardware | PAX A920Pro | Various EFTPOS terminals and POS registers |
| Commitment | Cancellable with 90-day notice | None |
| Payouts | 1 business day | Next day or instant for a fee |
| Accepted payments |         |
  |
EFTPOS terminals: varied vs single choice
When it comes to EFTPOS terminals, Square wins with its attractive selection of user-friendly card machines: Square Reader, Square Terminal and Square Handheld. To compare, Shift4 only has one card terminal: a PAX A920Pro.
Shift4 – one option only
Let’s start with Shift4’s wireless, portable terminal, the PAX A920Pro. It’s an update of the old PAX D210 terminal that the old Smartpay used for a decade, and it frankly took them a while to upgrade that even though it was outdated.
Photo: Mobile Transaction
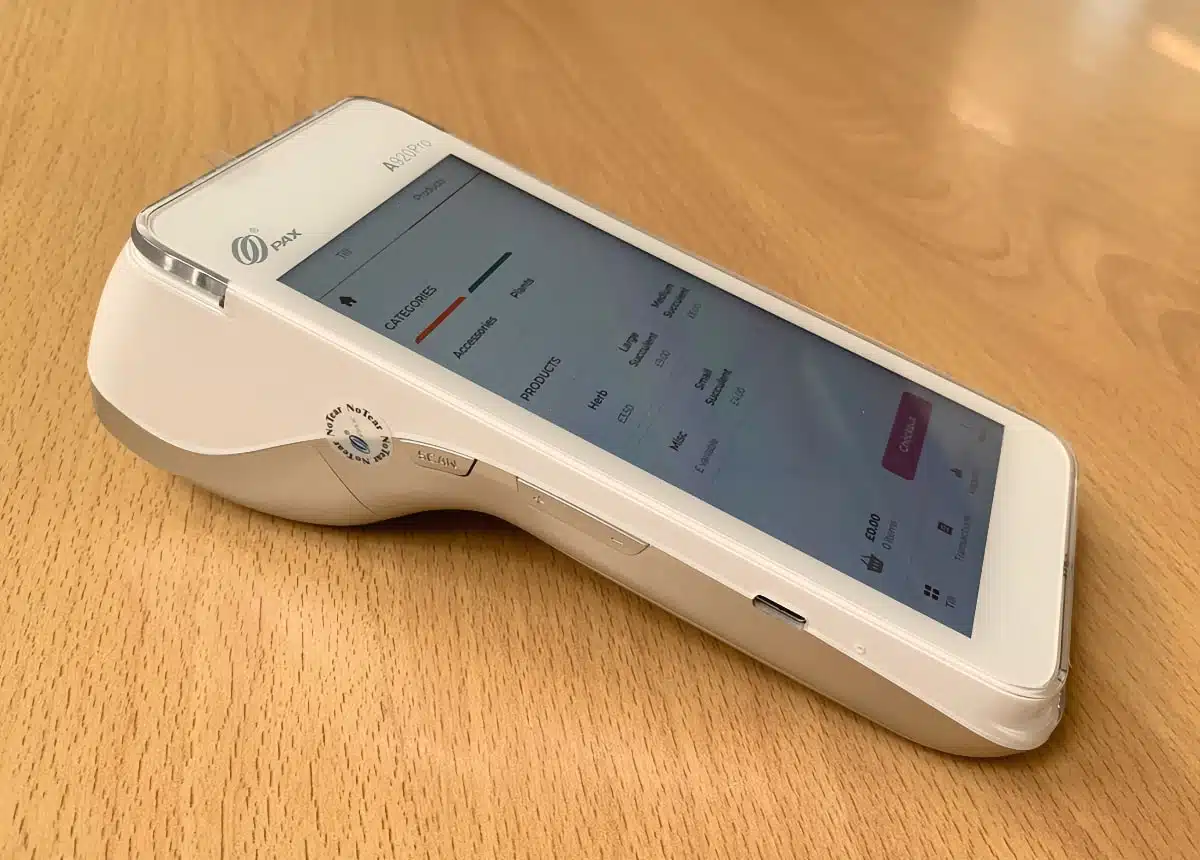
Shift4’s one and only EFTPOS machine is a PAX A920Pro model.
The Shift4 EFTPOS machine can be used for a fixed point of sale, portably around premises or on the go. It connects with broadband, WiFi or 4G with its included SIM card. The battery life is 8 hours from a full charge, although frequent usage would shorten this.
We’ve never had issues using it in our testing sessions – it’s a solid piece of equipment with a fast transaction speed. But its usefulness does depend on the payment software installed on it.
Photo: Mobile Transaction

PAX A920Pro has cameras for scanning (the underside one here pictured), but Shift4 doesn’t use it.
Shift4’s terminal has a large touchscreen, which some users prefer over push-buttons. It handles tips, surcharges, cash-outs and refunds, and potentially much more with additional apps.
“Shift4’s premium card machine, PAX A920Pro, is a great piece of equipment we’ve tested and used extensively, so it gets our full approval. But it’s a shame it doesn’t have POS features utilising its hardware functions.”
– Emily Sorensen, Senior Editor, Mobile Transaction
But Shift4 only has a simple card payment app installed, so the terminal’s built-in cameras for scanning, for instance, cannot be used.
Square – choice of terminals
In contrast, Square makes full use of its EFTPOS terminals’ features which we’ll move on to now.
First, we have the (literally) square-shaped Square Reader with no buttons. Its Bluetooth connects with an app on a smartphone or tablet to process card payments. This dual-device setup means the card reader is quite affordable and small, comfortably fitting in your pocket.
Photo: Mobile Transaction
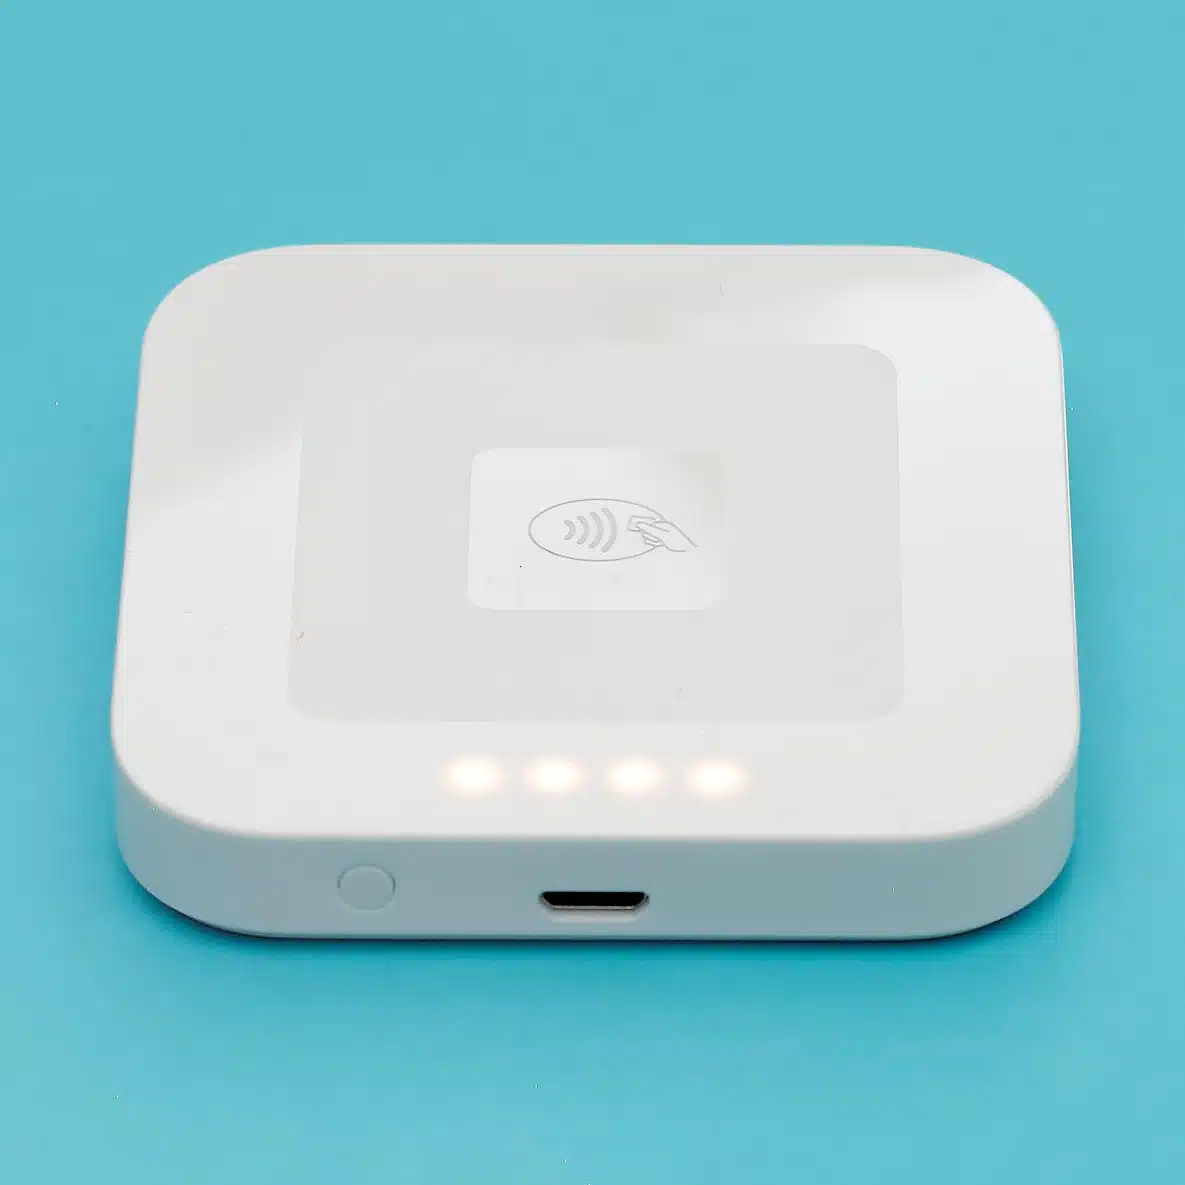
Square Reader is pocket-sized.
Photo: Mobile Transaction
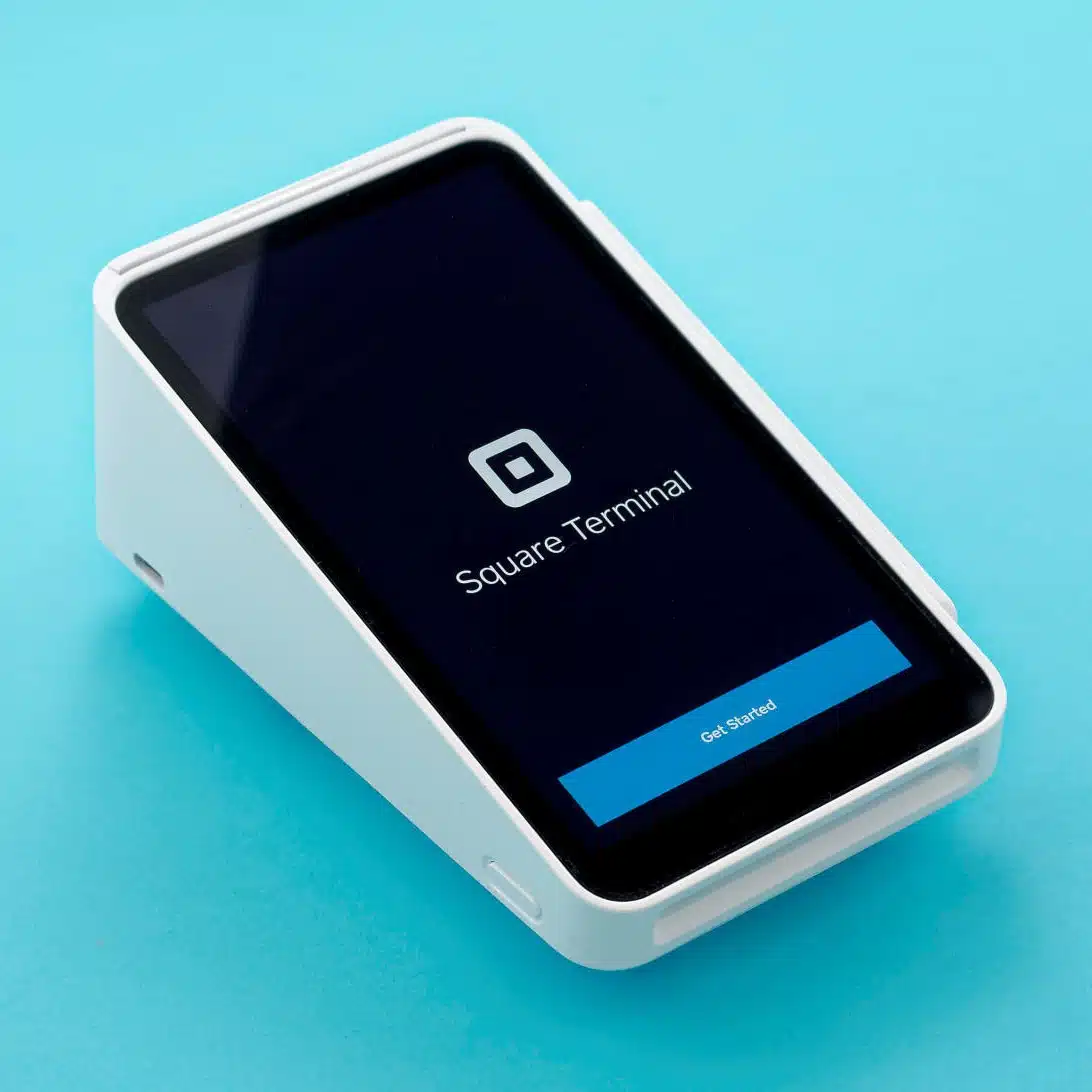
Square Terminal suits a counter.
Square Terminal and Handheld, on the other hand, are two bigger EFTPOS machines that work independently with WiFi only (not 4G). This means you can’t use them out and about with just a mobile connection like Square Reader or Shift4’s terminal.
“In our tests over the years, we’ve always been impressed by how many point of sale features Square’s products have, despite being so easy to use as well.”
– Emily Sorensen, Senior Editor, Mobile Transaction
Handheld and Terminal feature a large touchscreen with point of sale (POS) software installed. This general or specialised POS software (depending on context), although simple, has many more features than the Shift4 terminal, such as a product library and eat in/eat out settings.
Whereas Square Terminal has a built-in receipt printer like PAX A920Pro, Square Handheld doesn’t – it has a built-in barcode scanner instead. So I’d say the latter is better suited for retail shops, though its flat body (due to no bulky receipt printer) makes it great for restaurant table service too.
Photo: Mobile Transaction

Only Square sells POS registers too – pretty ones, like this pictured Square Stand for iPad.
You also buy into a Square system that can be upgraded to the stylish POS systems Square Register (with a card reader and touchscreen) or Square Stand (requiring an iPad). Shift4 simply doesn’t cater to that.
Pricing: no such thing as fee-free
A central aspect of Smartpay that Shift4 adopted was the “Fee Free” plan enabled through surcharging. Square later introduced surcharging as well, narrowing the differences between the companies. But following the Australian ban on surcharging from 1st October 2026, those options are ending. So what are the real differences of costs now?
Square is simplest with no minimum or fixed monthly fees
Square has no monthly fees, contract or setup fee. You simply purchase a card machine and pay only a fixed transaction fee (1.6%) when a payment takes place. If you process a refund, Square retains this transaction fee.
There’s only a monthly subscription for optional add-ons such as the advanced POS systems for the retail, restaurant and scheduling, customer loyalty and extended invoicing features. No other costs are required.
In addition, Square has no minimum monthly sales requirement, as opposed to Shift4’s more complicated pricing hinging on your sales volume.
Shift4 vs Square pricing:
| Cost | |
|
|---|---|---|
| Terminal purchase price | n/a | Square Reader: $65 incl. GST Square Terminal: $329 incl. GST Square Handheld: $349 incl. GST |
| Monthly fee | Rental: $0 or $34.95 + GST/mo | None (terminals are bought) |
| Contract | Cancellable with 90 days’ notice | None |
| Setup fee | None | None |
| EFTPOS transaction fees | Custom $100 + GST min. monthly fees required |
1.6% (any card) No monthly min. fees required |
| Payouts | Fee may apply | Free |
| Refunds | Fee may apply | Transaction fee is retained |
| Chargebacks | Fee may apply | Free |
Shift4 requires a $100 + GST monthly minimum of fees
At he point of writing, Shift4 still offers two distinct plans: Pass the Fees and Pay the Fees.
The latter plan is comparable to that of Square – one rate for all Mastercard and Visa cards. eftpos cards incur a flat fee instead of a percentage. If you want to accept Amex with a separate contract via Shift4, expect to pay above 3% (with Square, the Amex rate is 1.6%).
| Shift4 plans | Pass the Fees | Pay the Fees |
|---|---|---|
| Card turnover requirement | Any turnover | Any turnover |
| EFTPOS rental | Pay-As-You-Trade fee or $34.95 + GST/mo | $34.95 + GST/mo |
| Transaction fees | Variable fees passed on to customers as a surcharge | Fixed rate for Visa and Mastercard, fixed-cent fee for eftpos |
| Monthly min. fees | $100 + GST | $100 + GST |
*Card transactions per terminal. Does not include American Express, debit card or MOTO (Mail Order and Telephone Order) transactions.
The Pass the Fees plan means the transaction fee is passed on to customers as a surcharge, so it’s potentially “zero cost” in that regard. However, a monthly EFTPOS rental fee still applies, unless you opt to pay for rental through an additional transaction cost.
“Square doesn’t require a monthly sales volume, unlike Shift4 that requires you to sell enough to pay $100 + GST monthly in transaction fees on top of renting the EFTPOS machine.”
– Emily Sorensen, Senior Editor, Mobile Transaction
We think it’s confusing, to say the least, that Shift4 still advertises it’s Pass the Fees plan with the premise “never pay EFTPOS transaction fees again” just a few weeks before the nation-wide ban on surcharges – quite misleading for unknowing merchants.
Fees compared
For businesses exceeding $250k yearly in card sales, Square fees can be negotiated. Otherwise, you pay the fixed fee of 1.6% per EFTPOS transaction for any card type. Shift4’s fees are subject to negotiation and based on your turnover and industry, regardless of your business size.
The ability to offer Afterpay, a popular Buy Now, Pay Later option, through Square (for a 6% + 30¢ + GST fee) is attractive for some businesses.
Shift4 didn’t have a clear advantage since Square added surcharging – previously, Smartpay’s/Shift4’s main selling point. Square is generally more attractive with its lack of monthly fees for any business, transparent costs and value for money.
The only downside of Square is the upfront cost of purchasing an EFTPOS machine. With Shift4, you can avoid this since the machines are leased. You may also get lower rates from Shift4, but that’s not always the case.
Access to funds: genuinely fast with Square
When it comes to payouts, Square has two major advantages.
Shift4 deposits funds in your chosen bank account the following business day, if your bank accepts real-time deposits. That means you can access funds the day after each transaction, whereas Friday, Saturday and Sunday transactions all arrive on Monday.
In contrast, Square transfers arrive in your bank account the next morning. If your bank accepts real-time payments every day, you also receive funds during the weekend (though not after a public holiday).
While next-day funds is fast enough for many businesses, an additional option with Square has proven highly popular: with Instant Transfers, you can receive up to $5,000 of funds the same day within hours for an additional fee of 1.5% per transaction.
For many businesses we’ve talked to with time-critical purchasing needs, this is one of the attributes they value most about Square.
Reports and accounting: Shift4 very limited
Shift4 has some catching up to do with its online reporting interface.
Until a few years ago, Shift4 did not offer an online dashboard, but this is now standard for all users. The terminal also gives an overview of transactions for specific times like a date or shift, and transaction reports are sent via email.
In contrast, Square has long boasted an impressive online dashboard with a useful overview of transactions, along with sales reports identifying sales patterns in an easy-to-understand format. Reports are customisable, allowing you to analyse team performance, products, payment methods and much more.
Square allows you to integrate with accounting software Xero and QuickBooks. At the point of writing, Shift4 does not offer any accounting integrations. This can be bypassed if you connect the Shift4 terminal with a point of sale system that’s integrated with accounting.
Big point of sale differences
If you need a checkout system, this is where Square and Shift4 really differ.
Square takes the lead with its own point of sale (POS) software free of charge, along with three specialised systems for retail, restaurants and service appointments.
The old Smartpay used to offer a free POS app for phones, but it was quite basic and it’s no longer available through Shift4. In contrast, it’s always been possible to use Square Reader with the free phone or tablet app ‘Square Point of Sale’, which has been around for over a decade in other countries.
We know independent retailers and small food-and-drink businesses tend to find Square very easy to use. New features are continuously added on top of existing tools like real-time inventory management and sales analytics. We’ve always loved its ease of use, accessibility and simple layout from years of testing it.
Image: Mobile Transaction

The small but mighty Square Reader connects with very user-friendly POS apps.
The POS systems Square for Restaurants, Retail and Appointments (popular with health, fitness and beauty providers) come as free or paid versions. These take more time to get used to, but are richer with industry-specific features and suitable for a more sophisticated setup.
Square Terminal or Handheld essentially uses the Point of Sale app or versions of the Restaurants, Retail or Appointments apps on its touchscreen. Then there’s Square Register, a unique touchscreen checkout with Square’s own software.
All of these EFTPOS terminals are compatible with various POS accessories from cash drawers to receipt printers.
Image: Mobile Transaction
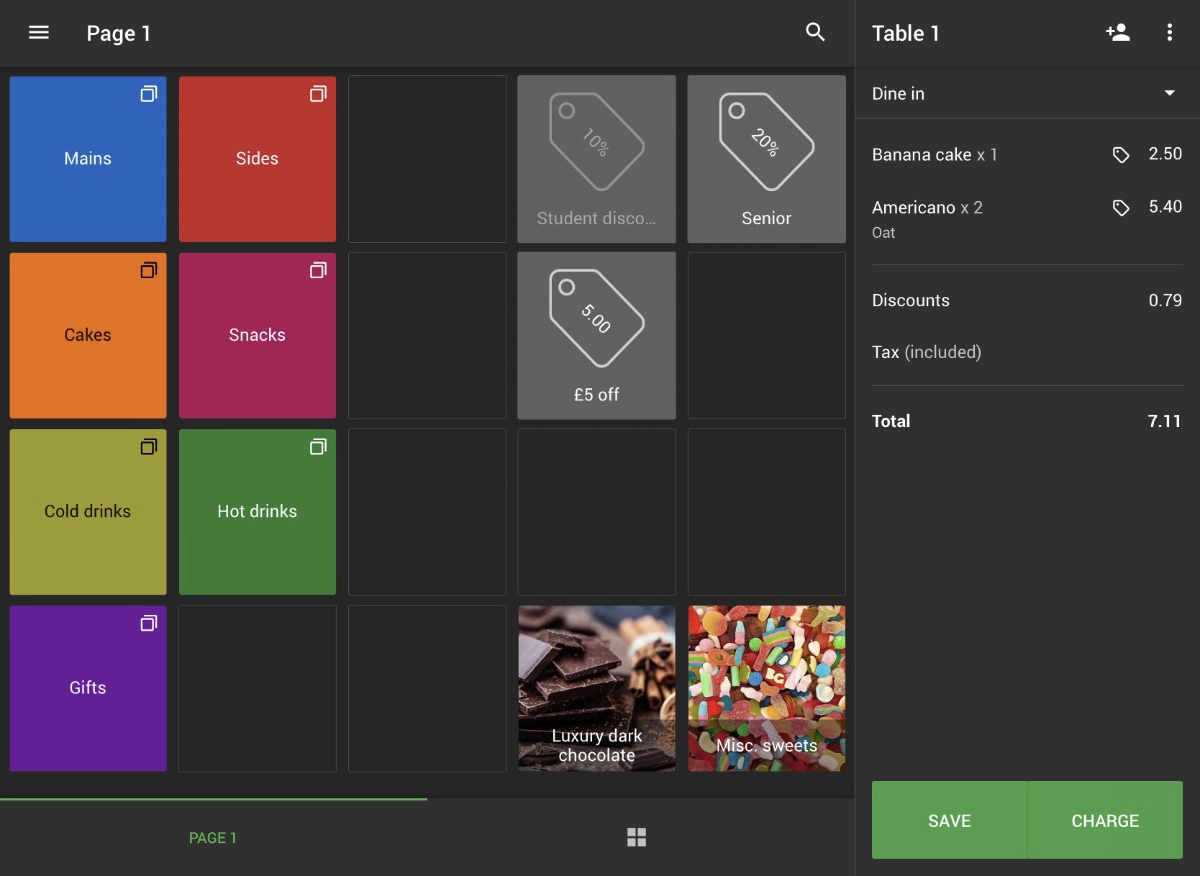
Loyverse, one of the POS apps compatible with Shift4, did well in our test, but can get pricey with add-ons.
Square integrates with external point of sale software too, for instance possBoss for hospitality, but also specialised systems like 360Winery and GRUBBRR for self-checkout kiosks (though Square has its own affordable Kiosk too).
If you require more advanced POS solutions, Shift4 integrates with e.g. Abacus, Casio and Loyverse, but some big names are missing, like Lightspeed and Epos Now. Still, integrating your Shift4 terminal with one of these systems ensures you can use it with a cash drawer, barcode scanner and other hardware.
Online and remote payments: Square excels
The contrast between payment options available through Shift4 and Square is stark. While Square offers just about any remote payment method you can think of, Shift4 is limited.
Shift4’s only remote payment option is keyed entry on its EFTPOS terminals. This allows you to accept card transactions from customers you’re talking to over the phone.
Square, on the other hand, offers many remote and online payment options, including:
- Online payments via a website (via Square or other ecommerce builder)
- Payment links
- QR codes (opening a link to a web payment)
- Email invoices
- Electronic gift cards
- Virtual terminal (for over-the-phone transactions)
- Keyed transactions through POS app
If you want to offer customers several payment methods from a single platform, Square is therefore the most attractive alternative.
Business loans: only one option
Another eye-catching feature unique to Square is their small-business loan between $100-$250,000. Square offers tailored loans based on your sales volume, account history and frequency of payments.
The loan doesn’t accrue interest, which is great, but it comes with a fixed fee agreed in advance. This charge and the loan are paid back automatically through a percentage of your transactions through Square. The higher your sales, the quicker your loan is repaid.
Note that this cash advance is only available to customers with a consistent sales history through Square, so new merchants do not immediately qualify.
Support and reviews: mixed experiences
Customer support is a vital part of any service, especially for business owners who often need urgent help.
If 24/7 customer support is important for your business, Square might not be best, unless you use Square Terminal or certain subscriptions that come with 24/7 support. But its products are designed so it’s easy to work out issues on your own, helped by the many guides online where it’s expected you look first for answers.
Reaching a real person is possible for all users through a live chat, phone call and email on business days between 9am-5pm Australian Eastern Time (AET).
Shift4 offers more personal support: a 24/7 support line with technical experts on hand to help, should the terminal be faulty, 365 days a year. The online support guides are not as elaborate as Square’s, though.
While Shift4’s support is more robust in theory, it’s clear from customer reviews it does not always meet users’ (higher) expectations.
The onboarding process is rated highly, but the continued service and troubleshooting support are often criticised for being slow.
While customers seem happy to ditch the big banks for Shift4, top ratings are not achieved for a speedy service. From businesses we have talked to, unclear fees and surprise charges are recurring issues.
Square’s users rave on about its user-friendliness and wide range of tools for all types of businesses.
Some of Square’s apps also come with reports of software glitches, though, such as issues pairing the card reader with the POS app. Overall, these issues are few compared with the number of users.
Verdict: more advantages with Square
For a business with card transactions of less than $10k monthly, the choice is pretty simple: Square. You get free access to many payment methods and business tools through a unified platform that’s easy to use, ultimately saving time and money.
Any “Zero Cost” solutions through surcharging is bound to end in October 2026, so you should choose the product with the best fees and setup for your business. For businesses exceeding $150k in card sales per year, the choice depends on what you value the most.
While Shift4 arguably has a better quality, more versatile EFTPOS machine, the terminal’s innate abilities are not fully exploited with its built-in payment software. Square offers many more tools and point of sale features through all their terminals.
If you can’t afford Square’s upfront purchase cost of an EFTPOS machine (though financing options are available), you might want to opt for Shift4’s terminal lease. But for businesses with an uneven cash flow, the instant transfer feature of Square is highly popular in Australia.
Whereas Square is generally better value for money, merchants might be able to get lower transaction rates with Shift4. The only way to know this is by contacting Shift4 for a quote that’s tailored to your business.