Charities used to rely on cash donations, but this is increasingly hard when many just carry a card or phone. That’s why many fundraisers look for card readers.
Other not-for-profit organisations need card machines for their charity shops, auctions, ticket sales, membership fees and more.
But getting a card machine as a non-profit organisation, individual fundraiser or community group isn’t as simple as it is for a business. Not all card machine companies allow donation payments, for example, but some do.
What should non-profits know, and which card machines are best for charities and fundraisers?
Do card machine providers accept charities?
Payment companies always have a list of restricted business types they don’t accept.
While most registered companies and sole traders fall under the “accepted merchant” category, not-for-profit organisations, community groups and individual fundraisers may not. That’s why you can’t order any credit card machine for your cause.
Charities, community interest companies (CIC) and non-profit organisations can, however, use their business registration details to get a card machine from certain companies.
But no card terminals in the UK accept private individuals for independent/personal use. You must sign up through some kind of charity, business or organisation registered in the UK to get a card reader from one of the below providers.
Personal users who just want to raise casual donations in their personal bank account can’t create a card reader account, unless they register as a representative or staff member of a charity or non-profit. This is a normal restriction in the UK, since payment companies have to comply with strict rules to prevent money laundering and legally questionable activities.
Also beware that if you already have a business with a card machine, this cannot typically be used for other purposes, since the card reader is registered for the specific business only. Failing to comply with that can result in a frozen account with your money stuck in there.
Pay-as-you-go providers
The most popular card reader companies in the UK also happen to be the go-to options for small charities: SumUp, Square, Zeller and PayPal (previously Zettle).
Their card machines are cheap, commitment-free and come with no monthly fees or hidden charges. You only pay a fixed rate per donation accepted.
Overview of card readers for charities and non-profit organisations:
| Solution | Card reader |
Transaction fee |
Website |
|---|---|---|---|
 |
Purchase: From £99 + VAT |
Pay-as-you-go: 1.3% for UK consumer Visa and Mastercard 1.99% for all other cards |
|
 |
Purchase: From £19 + VAT |
Pay-as-you-go: 1.75% for UK cards 3.25% for non-UK cards |
|
 |
Purchase: From £25 + VAT |
Pay-as-you-go: 1.69% for all cards £19/mo plan: 0.99% for most cards |
|
 |
Purchase: From £29 + VAT |
Pay-as-you-go: 1.75% for all cards |
Zeller
Relatively new in the UK, Zeller sells two very affordable card machines with a low, fixed card rate, no monthly fees and free online business account with optional expense cards.
The company accepts registered, not unregistered, charities. This includes various charitable entities, but it requires signing up to Zeller online to find out if your organisational structure is approved.
Photo: Mobile Transaction
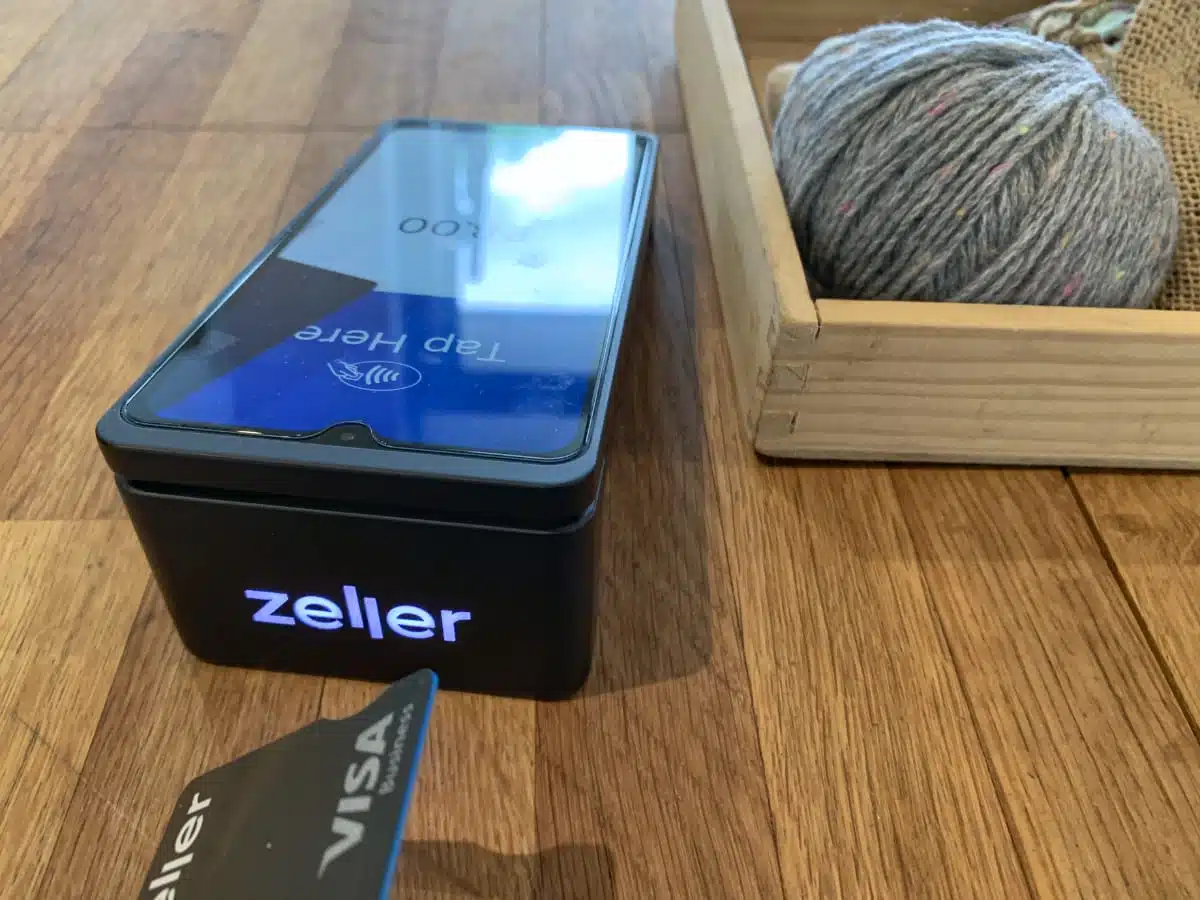
Zeller Terminal 1x is the cheapest card machine at £99 + VAT. It has a receipt printer, large touchscreen, and WiFi and 4G connectivity. Terminal 2 (pictured above) is pricier at £149 + VAT, doesn’t have a printer, but sits better on a counter.
“Zeller has the lowest UK card rate without a monthly fee and comes with its own business account you can link with crowdfunding websites. It’s a low-risk solution if the company approves your non-profit.”
– Emily Sorensen, Senior Editor, Mobile Transaction
They come with point of sale (POS) software that can show pre-entered amounts or shop products on the touchscreen, or you can enter a custom amount to accept by card. You can also record cash amounts to keep track of all donations.
Charities pay the same rates as other Zeller merchants: 1.3% for UK-issued, consumer Mastercard and Visa cards and 1.99% for all other cards via chip or contactless payments. Online donations cost 1.5% or 2.4% for the same cards respectively.
Square
Because Square advertises its products to businesses and sole traders primarily, we had to contact the company to know if they accept charities. The response was yes, Square generally accepts charities and non-profit organisations.
To sign up with Square, a trustee or authorised representative of the charity needs to select “Partnership” under ownership structure on the sign-up form. They can then enter their name and registration details of the charity organisation and order a card reader.
“The person signing up is the Account Owner in Square. This cannot be changed later, so make sure the right person takes charge of this – someone responsible and responsive.”
– Emily Sorensen, Senior Editor, Mobile Transaction
A bank account has to be linked to receive donations. This can either be in the name of the charity or Account Owner, in which case it can be a personal, UK-based current account accepting Direct Debits.
With Square Reader (£19 + VAT), the associated Point of Sale app lets you track donations and collect donor information. Through different user logins, you can also let volunteers and fundraisers use the same Square account to collect donations.
Photo: Mobile Transaction
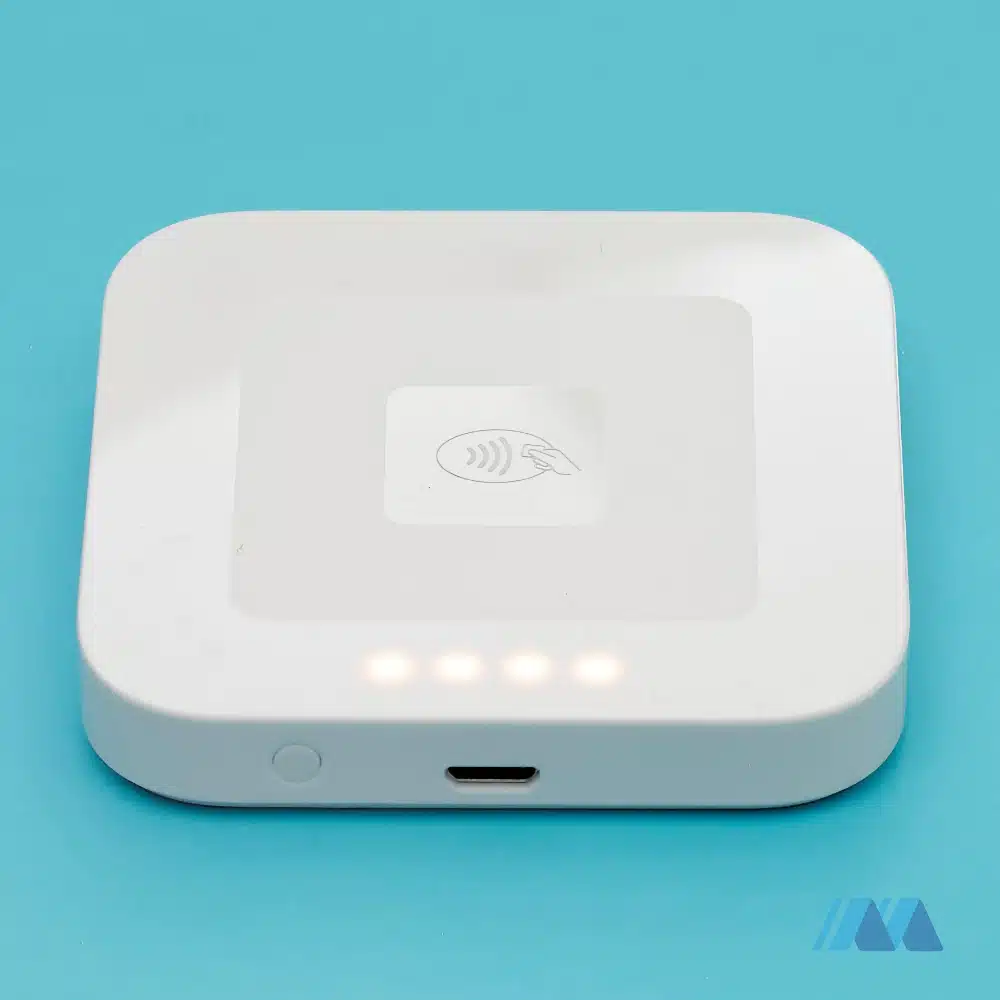
The standalone Square Terminal (below) or the new Handheld are more practical if you want to avoid using a phone app. They’re also pricier, but have all the software built in. They don’t work with mobile networks, though, just WiFi.
Photo: Mobile Transaction
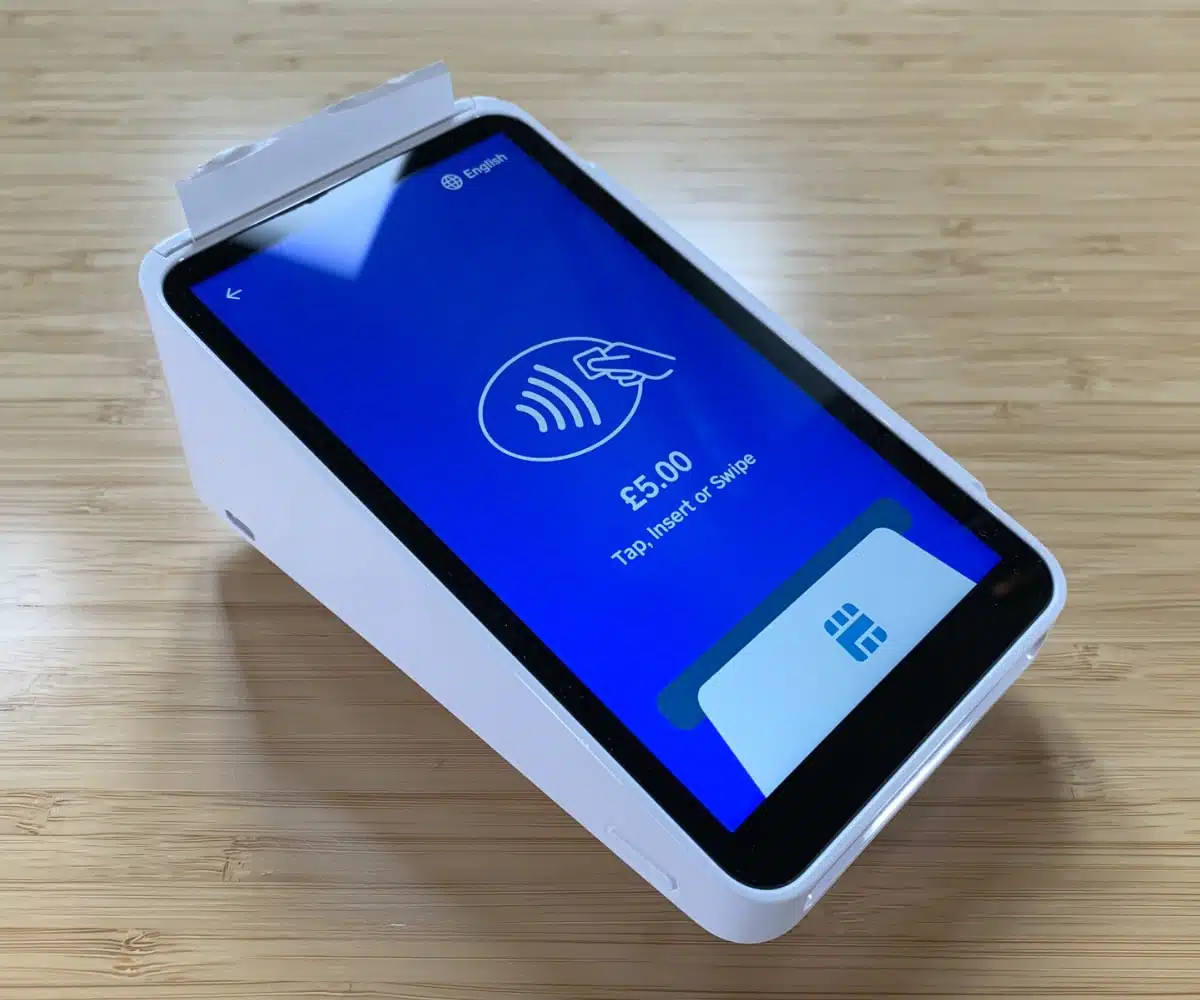
Just beware that Square’s standard rate, 1.75%, applies to UK-issued cards only. Foreign cards cost 3.25% via chip and tap – quite a difference if you have many international customers.
SumUp
SumUp accepts charitable or non-profit organisations, with these criteria:
“…they must at all times comply with applicable financial sanction regime regulations. SumUp products and services must in no way be used for raising funds in violation of financial sanction regime regulations, including but not limited to financing terrorism and/or use involving sanctioned countries.”
As with other card readers, SumUp lets you sign up easily online, inputting your non-profit or charity registration details as well as a bank account in the same name.
Just beware: SumUp has stated that they may restrict membership fees, political organisations and certain charities, but it depends on the nature of it.
SumUp Solo Lite (£25 + VAT) is the cheapest card reader. It works with an app that also accepts QR code payments in person.
Photo: Mobile Transaction
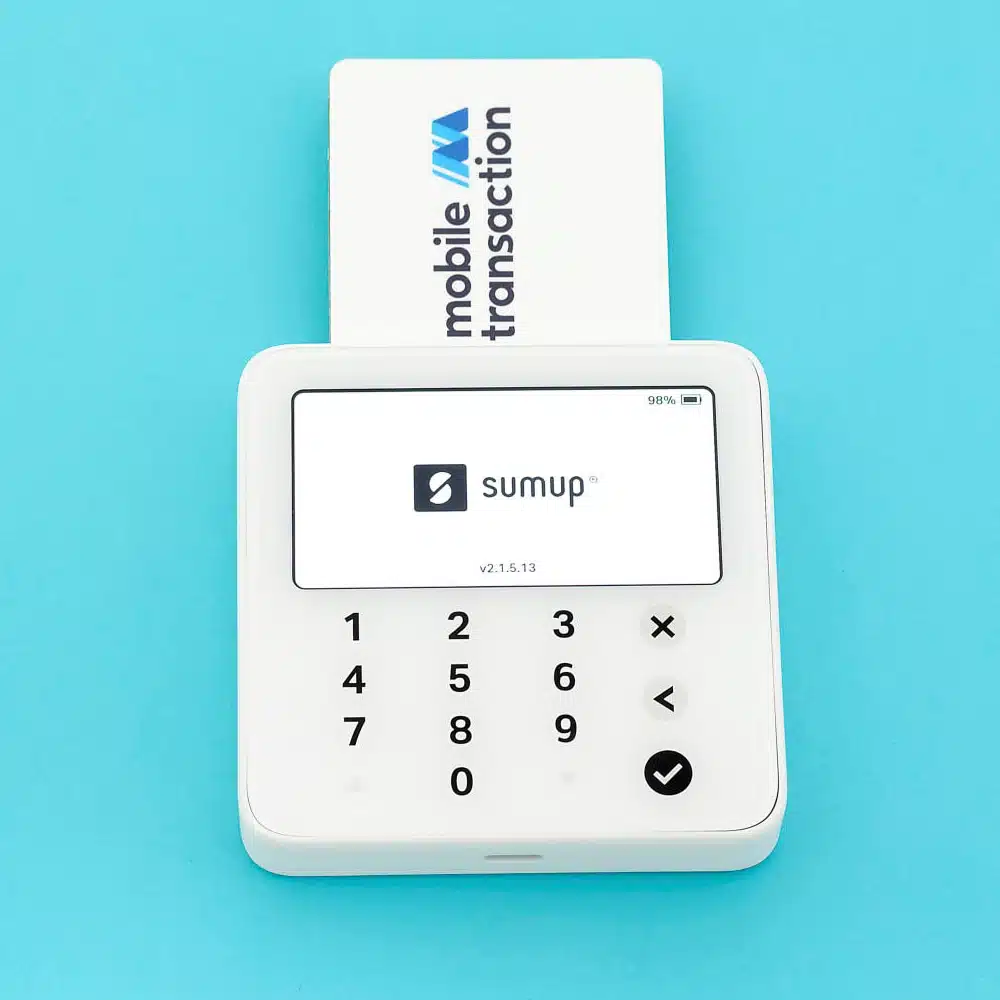
Pay-as-you-go transactions cost 1.69% for any card. If you subscribe to Payments Plus for £19 monthly, domestic consumer cards – the majority of cards used in the UK – only cost 0.99% and all other cards 1.69%. This plan can cut costs if you transact for more than £3,000 monthly.
PayPal Point of Sale (ex-Zettle)
PayPal does not advertise its card reader (£29 + VAT for the first one, £69 + VAT for extras) to charities or not-for-profits, so we had to ask the company about this. It turns out that PayPal donations are allowed when the cardholder is present, through PayPal Reader (pictured) or PayPal Terminal.
In contrast, charity donations are not allowed when the cardholder is not present, e.g. through payment links.
You can sign up as a charity on the website if it’s registered with the Charity Commission, Companies House or FCA. A bank account linked to the charitable organisation is required.
Alternatively, you can receive funds in a PayPal Businesses account and redistribute the funds from there online.
We should point out that PayPal reserves the right to increase fees at any time – which they might do eventually, knowing the company.
Photo: PayPal
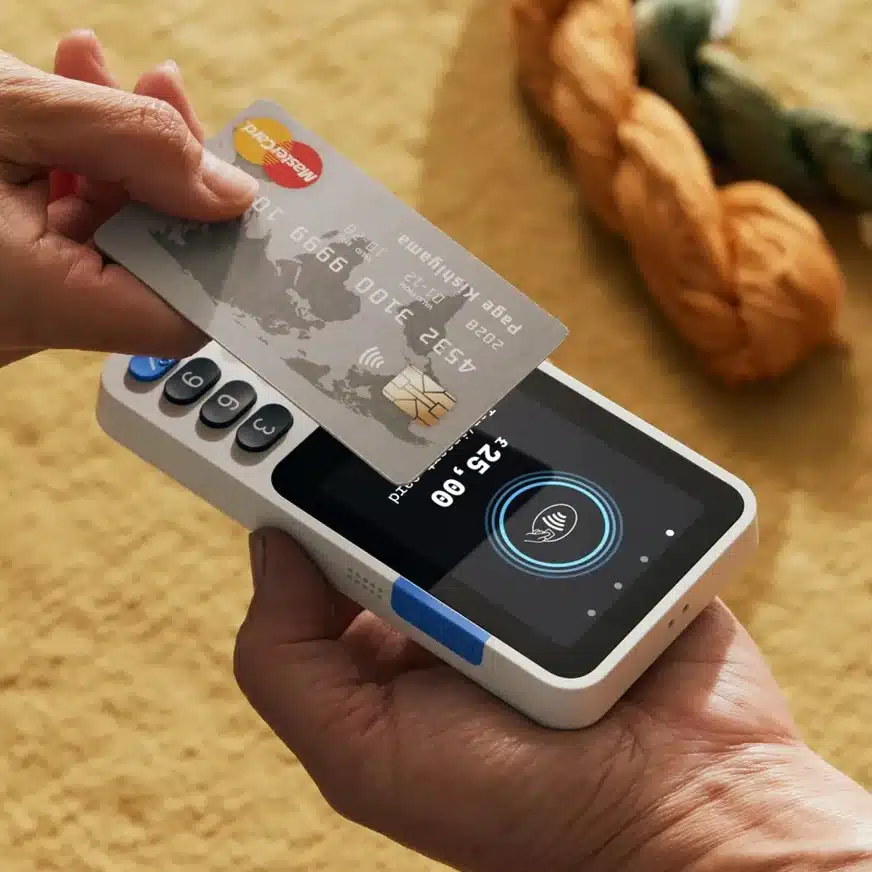
PayPal is known for its high, complicated charges online, so look out for any emails from them about a change of terms.
Payment providers with contract
Some merchant service providers and acquirers (that rent out card machines for businesses) accept registered charities, but these packages require commitment and ongoing fees. The deal might therefore not be great for those taking payments irregularly.
That said, the transaction fees can be competitive if you take a certain amount of payments over at least 12-18 months. So for steady charities, such as a fixed shop, café, club or local organisation, this type of provider would make sense.
Some charities also prefer the high-end card machine models offered by merchant service providers over an inexpensive card reader.
Merchant service providers accepting charities and non-profits:
| Provider | Card machine solution |
Website |
|---|---|---|
 |
Tailored onboarding with competitive, custom rates 12 months’ contract |
|
 |
Traditional provider serving many charities Up to 18 months’ contract |
|
 |
Requires a Santander charity account Up to 18 months’ contract |
|
 |
Excellent, personal service and no monthly fee 36-month contract |
These all have pros and cons, with contract length being one factor.
For instance, if you value an in-person installation and ongoing personal support, Flatpay should pique your interest. Its contract is 36 months, however, and you need to process at least £1k monthly through the card machine to avoid a monthly fee. Takepayments has a much shorter contract and more personalised plans.
Photo: Mobile Transaction
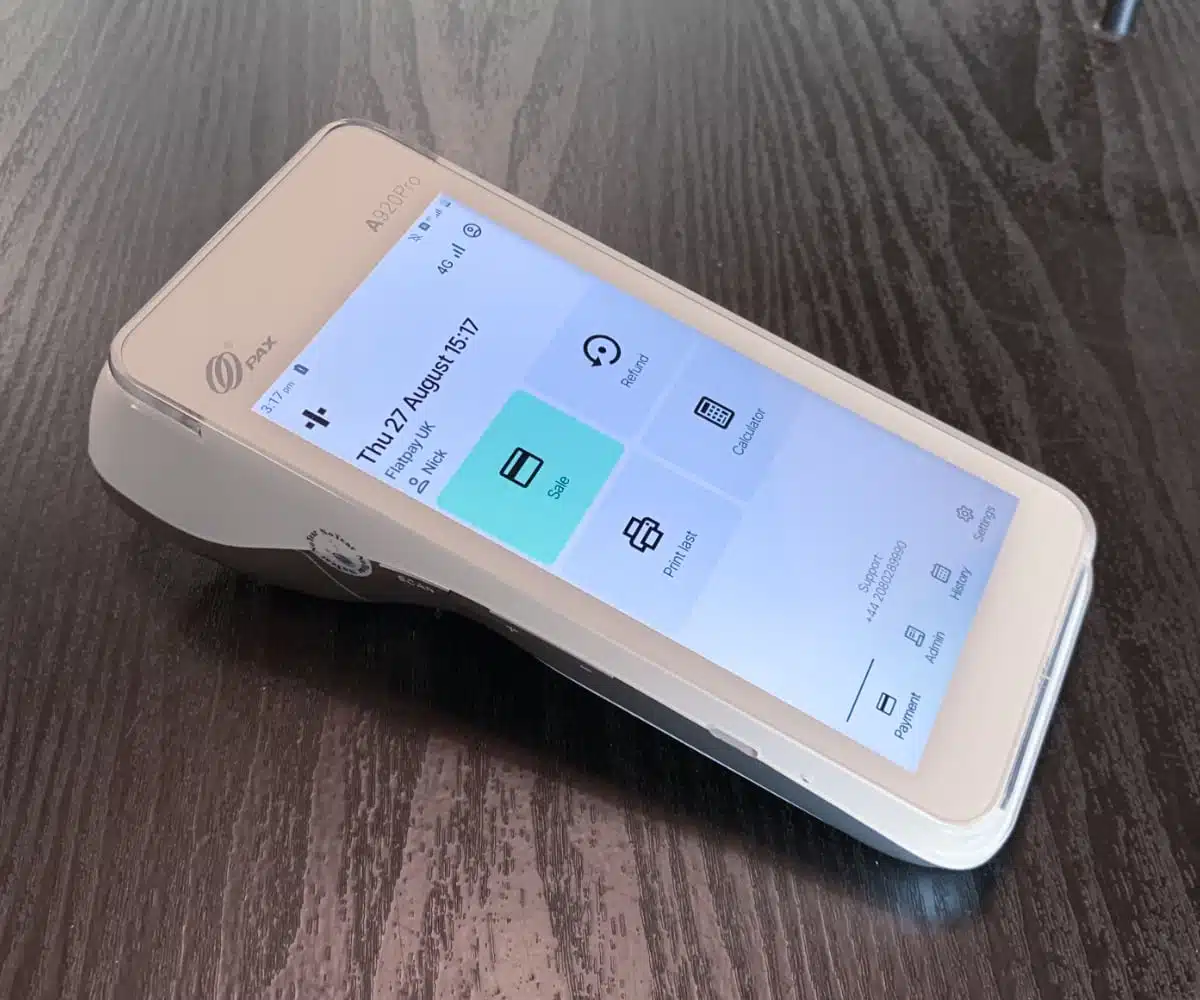
We tested Flatpay’s terminal (pictured), a high-quality PAX A920Pro model with fast processing.
Wireless Terminal Solutions (WTS) is another provider that caters to some charities, but it’s not as popular, modern or trusted as the above.
Other merchant service providers may offer plans for charities, but non-profit users are generally classed as higher risk and therefore often rejected.
Card machine solutions geared towards charities
A better option may be one the many companies that specialise in payment solutions for charity donations.
Many of these offer more than just a card reader. For example, card readers may be attached to a tablet or stand with big visuals advertising your cause. This, unfortunately, also makes it more expensive and requires monthly fees on top of an upfront setup or purchase cost for the contactless station.
Others offer a simple card reader with an app – this is generally cheaper.
Charity-focused companies that offer card machines:
| Charity solution |
Upfront cost |
Ongoing fees |
|---|---|---|
| GiveTap (via Square or Stripe) |
Square Reader + iOS/Android app: £19* |
£0-£29.99/mo, no contract 2.5% + VAT + Square or Stripe fee per donation |
| Give A Little (via SumUp or Stripe) |
SumUp Solo/Solo Lite + Android app: From £25* |
£0-£50*/mo No lock-in 1.49% per transaction (may change) |
| CollecTin | Donation station: From £200 |
From £0/mo From 1.49% per donation |
| Toucan Giving (prev. PayaCharity/LibertyPay) | Card machine or contactless station: From £179 |
£13.95+/mo 18-month lock-in 1.95% + Stripe fees per donation |
| GoodBox | Card reader or donation station: From £114* |
£7.50-£30+/mo 12+ months’ lock-in 1.59% + 10p per donation |
| GWD | Donation station: From £750* + £50* setup |
From £15*/mo 1.99% + 5p per donation |
| JustGiving (via Toucan Giving) |
Contactless station: Quote on request |
Quote on request Various contract lengths 5% per donation |
*Excluding VAT.
Some of these options do not show their pricing on the website. Instead, they will ask for details about your charity when you enquire about costs.
The first two options above avoid monthly fees from using the pay-as-you-go solutions Stripe, Square or SumUp. Give A Little, however, is more restricted as it only has an Android, not iPhone, app for its integration with a SumUp card reader.
It’s unlikely any of the above solutions accept anyone who’s not employed by, or an official representative of, the charitable or not-for-profit organisation.
Tap-on-phone gaining ground
The latest contactless payment technology to emerge in the charity sector is tap-on-phone, popularly called Tap to Pay – using your phone as a card machine.
This allows donors, sponsors or customers to just tap their card or contactless mobile wallet (Google Pay, Apple Pay) on the charity’s smartphone to accept the payment. No card reader is required here, just an NFC-enabled phone with Tap to Pay enabled in a suitable app.
Most commercial payment companies accept Tap to Pay, including Square, SumUp and PayPal that all accept non-profit entities.
Charity-focused payment companies offering Tap to Pay include:
- Give A Little
- givestar
- GiveTap
- Toucan Giving
All of these work on both iPhone and Android phones.
Alternative card payment methods for charities
If you don’t want tap-to-pay, consider online charity options such as:
- Text-to-donate (e.g. Donr)
- QR code payments (e.g. SumUp)
- Payment links (e.g. Zeller, Square)
- Referring people to a fundraising page (e.g. JustGiving, PayPal)
- Easy bank payments (e.g. GoCardless)
Except for bank payments, these tend to have higher transaction fees, so getting a card reader is usually cheaper in the long run.
Also, not everyone can – or likes to – pay online, so it’s generally better with a mix of payment options to cater for accessibility needs and user preferences.
Summary
Charitable donations are a cornerstone for good causes, but now that few people carry cash, getting a card reader is important to avoid losing out on too much money.
Fortunately, low-cost card machines from Square, Zeller, SumUp and PayPal allow non-profits to accept payments without a contract or fixed subscription. The only hindrance is registration, since you can only get a functioning card reader with your organisation’s consent and registration details.
Bigger, more established charities with in-person donors might prefer donation kiosks from specialist charity payment companies. These typically cost hundreds of pounds upfront plus ongoing charges.
Traditional merchant service providers like Worldpay and Elavon are mainly for regular payments above a certain sales volume.